The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Street views · Archive
Friday, September 11, 2026
▶ The 2-minute market brief · video · 1.25x
Listen · the 2‑minute market briefToday's markets in two minutes. Tap to play
Prefer audio only? Listen here.
Markets at a glance
Last price as of Fri, Sep 11, 5:34 AM ET · 1-day change vs prior settle. Continuous front-month futures. Click price for news.
This slot is empty today. Take a day from $250 →
Downey's Take
Brent $105, down about $3 (3%), WTI $100, down $3, after an FT story around 8:20 pm ET Thursday: Iran and Gulf states to meet in a push for a Hormuz deal. Oman is brokering a temporary corridor. GCC foreign ministers plus Iran’s FM are slated for Monday, Sep 14, in Salalah, Oman, the first GCC-Iran ministerial since the war started Feb 28. Separately, Thursday night OSINT chatter of a possible Houthi hit on the Saudi East-West pipe was discounted by the market: same pipe Saudi patched in days after an April 2026 hit.
Zinc down $117 (-3.2%) on White House hesitation on refined copper tariffs triggering broad base metals profit-taking and China export concerns.
Cocoa up $177 (+3.0%) on West African supply risks and El Niño concerns building.
Tin down $1582 (-2.8%) on broader base metals selloff amid tariff uncertainty and technical pullback.
Copper down $409 (-2.8%) on White House hesitation on refined copper tariffs easing import premium and sparking liquidation.
Isobutane up 3.3 cents/gal (+2.4%) on gasoline blending waivers and high cracks.
Kicker: Goldman Sachs recommends long copper, short aluminum (Dec27) on unique mine supply constraints for copper versus ample aluminum supply growth.
Zinc down $117 (-3.2%) on White House hesitation on refined copper tariffs triggering broad base metals profit-taking and China export concerns.
Cocoa up $177 (+3.0%) on West African supply risks and El Niño concerns building.
Tin down $1582 (-2.8%) on broader base metals selloff amid tariff uncertainty and technical pullback.
Copper down $409 (-2.8%) on White House hesitation on refined copper tariffs easing import premium and sparking liquidation.
Isobutane up 3.3 cents/gal (+2.4%) on gasoline blending waivers and high cracks.
Kicker: Goldman Sachs recommends long copper, short aluminum (Dec27) on unique mine supply constraints for copper versus ample aluminum supply growth.
Drivers and the Kicker trade idea are sourced from third-party news and bank or desk commentary. Informational only, not BoxWood trade advice.
The marquee commodity stories of the day
Saudi oil output hits 2026 low on Houthi threats
Verity Ratcliffe · Financial Times · Thu, Sep 10, 2026
Saudi Arabia told OPEC it produced 6.2 million barrels a day in August, the lowest monthly figure in 2026 and 23% lower than in July. Houthi rebels announced a maritime embargo against the kingdom’s ports at the end of July, deterring ship operators and forcing output cuts as exports fell to about 3.1 million b/d. Read →
Hormuz vessel transits fall to seven on Wednesday
Reuters · Thu, Sep 10, 2026
Vessel transits via the Strait of Hormuz fell on Wednesday to seven from 12 the previous day, below the 10-day average of 14. One VLCC exited carrying nearly 2 million barrels of crude; no LNG tankers left the strait. Read →
US diesel average tops $6/gallon for first time
Reuters · Thu, Sep 10, 2026
The U.S. national average price of diesel surpassed $6 a gallon for the first time ever on Thursday. Surging crude prices from the Iran conflict and Ukrainian attacks on Russian refineries have squeezed global distillate supplies. Read →
Copper set for first weekly loss since June
Bloomberg · Thu, Sep 10, 2026
Copper headed for its first weekly loss since June on concern the US is pushing back a decision on import tariffs. Futures steadied after losing 3.6% in London on Thursday, drawing back from a record earlier in the session. Read →
Brent tops $100 on Mideast escalation
Anthony Harrup · Wall Street Journal · Wed, Sep 9, 2026
Brent crude futures settled at their highest level since May 22 as strikes between the U.S. and Iran escalate and Houthis step up attacks on Saudi oil facilities. Brent settled up 3.4% at $101.21 a barrel, and WTI rises 3.2% to $96.05. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 4US Natural Gas 3Wet Gas, NGLs & Petchems 3Global Nat Gas & LNG 4Coal 2Agriculture 4Base Metals 3Iron Ore & Steel 3Precious Metals 2Rare Earths & Critical Minerals 3Shipping & Freight 2Environment 2Real-World Assets & On-Chain Commodities 3Corporate & Deals 4Regulation & Government 4Social buzz 5Watch & Listen 3Prediction Markets
Markets News
Oil
What's moving · Escalating tanker attacks and Houthi Red Sea advances drive Brent above $108 and WTI above $102 on supply fears.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude | 100.31 | -2.1% -2.17 |
+74.7% | +60.0% | +42.4% |
| Brent | 104.84 | -2.6% -2.79 |
+72.3% | +56.5% | +42.6% |
| RBOB Gasoline | 3.353 | -1.2% -0.040 |
+96.6% | +68.9% | +55.2% |
| Heating Oil | 5.026 | -0.6% -0.032 |
+137.0% | +119.5% | +132.8% |
| NY RBOB Crk $/bbl |
40.51 | +1.2% +0.47 |
+185.1% +26.30 |
+95.7% +19.81 |
+99.5% +20.20 |
| NY HO Crk $/bbl |
110.77 | +0.8% +0.83 |
+250.0% +79.12 |
+230.7% +77.28 |
+448.4% +90.57 |
| NY 321 Crack $/bbl |
63.93 | +0.9% +0.59 |
+219.3% +43.91 |
+156.1% +38.97 |
+215.4% +43.66 |
Oil set to close week above $100 amid Mideast attacks
Reuters · Fri, Sep 11, 2026
Brent and WTI remained on track for their strongest weekly gain since mid-July despite Friday slips, with weekly advances near 13%. US diesel prices hit a record above $6/gallon for the first time. Houthis advanced on Red Sea coastal areas and tanker attacks continued, keeping Hormuz transits in single digits. Read →
Brent tops $109 as Mideast tensions fuel supply worries
Bloomberg · Thu, Sep 10, 2026
Brent briefly topped $109/bbl as Saudi Arabia reported August output at its lowest since 1990 and Houthis pushed toward the Bab el-Mandeb Strait. Tehran resumed ballistic missile production, per WSJ, while the US-Iran conflict showed no signs of quick resolution. The moves compounded shipping disruptions and inventory tightness. Read →
Russia crude output falls in August on Ukraine strikes
Bloomberg · Thu, Sep 10, 2026
Russian crude production averaged 8.718 million b/d in August, down 160k b/d from July per OPEC secondary sources, the largest monthly drop since December. Ukraine intensified strikes on Russian oil assets, widening supply-side pressure alongside Middle East disruptions. Read →
OPEC cuts 2026 demand growth forecast fifth time
Reuters · Thu, Sep 10, 2026
OPEC lowered its 2026 world oil demand growth forecast to 380k b/d, the fifth straight cut. The revision came as OPEC output fell 640k b/d in August amid Saudi export disruptions and a US blockade on Iran shipments. Read →
US Natural Gas
What's moving · Record Lower 48 output at 113.4 bcfd and 40 Bcf storage build above expectations pressure Henry Hub to two-week low near $2.78.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub | 2.814 | -0.7% -0.020 |
-23.7% | -4.3% | -46.2% |
Natgas futures slide 2% to two-week low on record output, ample storage.
Reuters · Thu, Sep 10, 4:00 PM ET
US natural gas futures for October delivery fell 4.5 cents or 1.6% to $2.777/MMBtu on Thursday. Record Lower 48 output reached 113.4 bcfd in September so far per LSEG, while the EIA reported a 40 Bcf injection for the week ended September 4, exceeding the 31 Bcf consensus and leaving stocks 4.8% above the five-year average. The build and supply glut outweighed warmer weather support for power burn and LNG flows near 18.3 bcfd. Read →
EIA posts 40 Bcf injection, above 31 Bcf forecast, deepening y/y deficit.
Andrew Baker · Natural Gas Intelligence · Thu, Sep 10, 11:21 AM ET
The EIA reported a 40 Bcf net injection for the week ended September 4, lifting Lower 48 working gas to 3,254 Bcf. Stocks sit 79 Bcf or 2.4% below year-ago levels and 148 Bcf above the five-year average of 3,106 Bcf. East and Midwest drove most of the build while South Central salts saw a draw; the larger-than-expected print kept futures pressured despite tightening relative to last year. Read →
40 Bcf storage build exceeds forecasts, futures slip below $2.80.
Kevin Dobbs · Natural Gas Intelligence · Thu, Sep 10, 4:05 PM ET
October NYMEX futures traded around $2.786/MMBtu midday after the 40 Bcf EIA print beat the 31 Bcf expectation. The injection exceeded seasonal norms but reflected continued ample supply from near-record production. LNG feedgas and some production dip provided minor support, yet the overall balance kept prices in retreat amid forecasts for milder fall demand. Read →
Wet Gas, NGLs & Petchems
What's moving · Mont Belvieu propane +2.3% to 84.6¢/gal on export demand and seasonal heating pull amid tight global LPG balances.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.250 | +0.7% +0.002 |
+5.5% | +3.2% | -32.8% |
| Propane C3 $/gal |
0.846 | +2.3% +0.019 |
+37.2% | +20.0% | -30.3% |
| Isobutane IC4 $/gal |
1.454 | +2.4% +0.033 |
+87.0% | +63.1% | +6.0% |
| N-Butane NC4 $/gal |
1.264 | +1.7% +0.021 |
+69.6% | +43.0% | -11.4% |
| Pentane C5 $/gal |
2.049 | +2.4% +0.047 |
+74.8% | +57.2% | +24.6% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 6 | unch | +7 | +2 | +4 |
| C3 Frac Sprd ¢/gal | 59 | +2 | +31 | +15 | -15 |
| C2 vs NWE Naph $/mt | -675 | -30 | -370 | -301 | -298 |
| C3 vs NWE Naph $/mt | -427 | -22 | -260 | -233 | -395 |
| C5 as % WTI | 86 | +4 | unch | -2 | -12 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
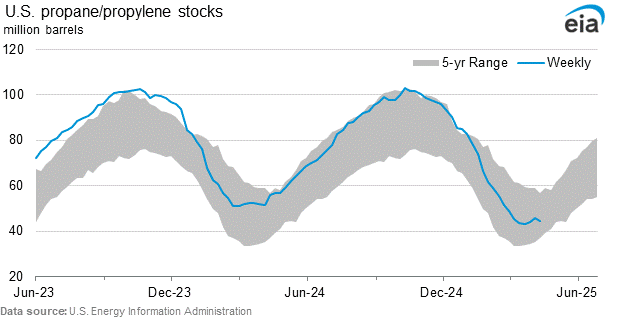
EIA propane stocks · week ending Fri, Sep 4
A 3.1 mb build took US propane stocks to 110.5 mb, 23.6 mb (27%) above the five-year average and 12.9 mb above a year ago. Exports ran 1,960 kb/d (-193 kb/d w/w) against production of 2,953 kb/d.
US stocks 110.5 mb +3.1 mb w/w |
Year ago 97.6 mb |
5-yr avg 86.9 mb |
Gulf Coast 70.2 mb PADD 3 |
Midwest 26.6 mb PADD 2 |
Exports 1,960 kb/d -193 kb/d w/w |
Source: EIA Weekly Petroleum Status Report · Full EIA report →
Clariant wins CATOFIN catalyst deal for 1.2M tpa China PDH unit.
Clariant · Thu, Sep 10, 2026
Clariant was awarded the catalyst and HGM supply contract by Zhejiang Petroleum & Chemical (ZPC) for the world’s largest licensed propane dehydrogenation unit (1.2 million metric tons per annum propylene capacity) in Zhejiang Province, China. The CATOFIN technology from Clariant and Lummus will convert propane feedstock, supported by ZPC’s upstream refinery expansions, into high-value petrochemical derivatives. This marks another major win for CATOFIN, underscoring strong Asian PDH demand for US-origin propane amid global propylene needs. Read →
Dow mulls exit from $20B Sadara chemicals JV with Aramco.
Reuters · Wed, Sep 9, 2026
Dow is considering exiting its 35% stake in the $20 billion Sadara Chemical Co. joint venture with Saudi Aramco in Jubail, Saudi Arabia, as part of portfolio reshaping amid a prolonged petrochemical downturn. The complex produces over 3 million metric tons per year of chemicals and plastics; Dow reported a negative $793 million investment balance as of June 30 and suspended loss recognition in Q1 2026. Aramco could acquire the stake or other investors could bid, with no final decision yet; the move aligns with Dow’s broader cost-cutting and non-core asset reviews. Read →
Haldia plans 30% LPG substitution in naphtha cracker for supply security.
Reuters · Wed, Sep 9, 2026
India’s Haldia Petrochemicals is retrofitting its 700 ktpa ethylene naphtha cracker with Lummus technology to enable up to 30% LPG substitution as a hedge against Middle East supply disruptions from the US-Iran conflict. The company, which has term naphtha contracts with QatarEnergy, KPC and ADNOC, turned to spot cargoes after Hormuz shipments stalled and plans domestic LPG sourcing from IPPL plus imports from all available origins. The shift highlights Asian petchem operators’ move toward flexible LPG feedstock amid naphtha tightness and supports incremental US propane demand. Read →
Global Nat Gas & LNG
What's moving · TTF falls 2 to 3% today to €80/MWh as storage refill pace and milder signals ease immediate winter fears amid lingering LNG supply concerns.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
80.56 | -1.8% -1.49 |
+186.1% | +146.6% | +31.5% |
| Dutch TTF $/MMBtu |
27.39 | -1.8% -0.51 |
+186.1% | +146.6% | +31.5% |
| JKM $/MMBtu |
24.82 | +0.5% +0.13 |
+158.4% | +118.5% | +31.9% |
TTF holds near three-year highs on low EU storage, LNG risks
Giulia Petroni · Wall Street Journal · Thu, Sep 10, 2026
European natural gas prices remain at their highest since late 2022, with the Dutch TTF benchmark trading near or above €80/MWh. EU gas storage sits at roughly 67% full, well below the 84% five-year average, while Middle East LNG disruptions heighten winter supply risks. A widening TTF-JKM spread adds support by increasing competition for flexible cargoes. Read →
Ignitis signs 10-cargo LNG deal with EQT unit for 2027 to 2036
Ignitis Grupe / GlobeNewswire · Wed, Sep 10, 2026
Lithuanian utility Ignitis will buy one LNG cargo (1 TWh) per year from an EQT Corp subsidiary under a 2027 to 2036 contract won via tender. Pricing links to Henry Hub and TTF benchmarks to manage volatility for residential customers. The deal diversifies supply and requires regulatory and security approvals. Read →
Arctic LNG 2 files $1B claim vs Hanwha over canceled tankers
Reuters · Mon, Sep 8, 2026
Arctic LNG 2, 60% owned by Novatek, seeks about $1 billion in damages from Hanwha Ocean at the Singapore International Arbitration Centre over terminated Arc7 tanker contracts hit by sanctions. The project has faced repeated setbacks, limiting its ability to ramp exports to Asia despite some recent output gains. Read →
Arctic LNG 2 hits record output amid expanded dark fleet
Bloomberg · Tue, Sep 9, 2026
Novatek’s Arctic LNG 2 produced over 27 million cubic meters per day in July-August, nearly double August 2025 levels, aided by more dark-fleet tankers routing cargoes to China. Sanctions continue to constrain full commercial operations and dedicated ice-class shipping capacity. Read →
Coal
What's moving · IEA lifts 2026 global coal demand forecast 1.2% to record 8.94 Bt on Middle East-driven gas prices and El Nino.
Bloomberg: Coal demand hits record on soaring gas prices.
Bloomberg · Thu, Sep 10, 5:16 AM ET
The IEA report highlights how elevated natural gas prices and El Nino-driven cooling needs are pushing coal consumption higher than prior forecasts. Coal demand is now expected to reach a record this year, with potential for further increases in 2027 if LNG disruptions persist. The update reverses earlier expectations of a decline and underscores coal's role amid energy market volatility. Read →
Transnet aims for 65 Mt coal exports amid rail recovery.
Liesl Peyper · Miningmx · Thu, Sep 10, 9:49 AM ET
South Africa's Transnet reported coal exports rose to 58.5 Mt in the latest period and targets 65 Mt delivered exports, supported by improving rail performance. CEO Michelle Phillips noted ongoing debt and cash constraints limit faster growth despite volume gains. Richards Bay Coal Terminal volumes are also tracking toward higher annual totals. Read →
Agriculture
What's moving · USDA September WASDE and crop report lands today amid China soybean buys and Black Sea disruptions.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn | 528 | -1.1% -6 |
+19.9% | +32.3% | +6.2% |
| Wheat | 739 | -0.4% -3 |
+45.7% | +46.8% | +9.5% |
| Soybeans | 1,318 | -1.1% -14 |
+27.9% | +28.5% | +3.6% |
| Sugar | 19.45 | -1.5% -0.30 |
+29.6% | +23.2% | +2.5% |
| Coffee | 288.0 | -0.1% -0.1 |
-17.4% | -29.9% | +56.2% |
| Cocoa | 6,139 | +3.0% +177 |
+1.2% | -16.1% | +129.3% |
| Cotton | 87.63 | -0.7% -0.59 |
+36.0% | +34.1% | -7.4% |
China buys 1M tons US soybeans ahead of Xi visit
Ella Cao and Naveen Thukral · Reuters · Thu, Sep 10, 5:20 AM ET
Chinese state buyers including Sinograin purchased about 1 million metric tons of US soybeans this week for December-February shipment from Gulf ports. The buys bring China near half its 25 million ton annual commitment through 2028 and coincide with tightening Brazilian supplies. USDA confirmed 340,000 tons sold to China plus 100,000 tons to unknown destinations on Wednesday, supporting soybean futures near multi-year highs. Read →
USDA September crop report due today after grain rally
Global Agriculture · Fri, Sep 11
USDA releases its September WASDE and Crop Production reports at 12:00 PM ET today. Analysts expect corn yield trimmed to 178 to 179 bushels per acre from August's 180.7 and soybean yield near 52.4 to 52.5 bushels per acre. Markets await confirmation of late-summer yield stress after December corn rose nearly 90 cents and November soybeans exceeded $13 per bushel since the August report. Read →
Chicago corn, soybeans edge higher ahead of USDA data
Reuters via Business Recorder · Fri, Sep 11
CBOT corn rose 0.6% to $5.30 to 3/4 per bushel and soybeans gained 0.5% to $13.16 per bushel Thursday while wheat was little changed. Traders trimmed risk ahead of Friday's USDA report and monitored Russia-Ukraine developments that have disrupted Black Sea grain flows. Prices retreated from three-year highs as diplomatic efforts encouraged profit-taking. Read →
Russia zeros wheat export duties amid Black Sea attacks
Global Agriculture · Thu, Sep 10
Russia eliminated export duties on wheat, corn and barley effective September 1 to support exporters after Ukrainian strikes damaged Black Sea terminals including Novorossiysk. The Azov-Black Sea basin capacity has fallen sharply, cutting Russian and Ukrainian wheat shipments to roughly 2 million tons in August versus over 5 million tons a year earlier. The move highlights persistent export bottlenecks supporting global grain prices. Read →
Base Metals
What's moving · US tariff hesitation triggers sharp copper pullback from record highs as arbitrage premium collapses.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
14,414 | -0.1% -21 |
+16.1% | +42.5% | +49.8% |
| Copper SHFE $/mt |
14,427 | -2.8% -409 |
+13.6% | +45.8% | +51.2% |
| Aluminium SHFE $/mt |
3,193 | -1.5% -48 |
+7.3% | +24.4% | +10.1% |
| Zinc SHFE $/mt |
3,538 | -3.2% -117 |
+17.8% | +28.7% | +15.9% |
| Nickel SHFE $/mt |
16,610 | -2.0% -342 |
-1.9% | +9.3% | -19.1% |
| Lead SHFE $/mt |
2,128 | +0.3% +6 |
-3.4% | +2.1% | +4.4% |
| Tin SHFE $/mt |
54,302 | -2.8% -1,582 |
+29.3% | +60.1% | +58.9% |
White House stalls copper tariff plan over cost concerns.
Jarrett Renshaw and Ernest Scheyder · Reuters · Thu, Sep 10, 10:08 AM ET
The White House has not decided on refined copper import tariffs after weighing higher manufacturing costs against domestic mining incentives. Copper prices hit records on tariff expectations that drove massive US inflows and global inventory drains. The stall removes a key premium, with LME three-month copper falling over 3% and COMEX-LME spread turning negative. Read →
US copper premium sinks on tariff stall report.
Reuters · Thu, Sep 10, 1:31 PM ET
The premium for shipping copper to the US fell sharply after the Reuters tariff stall report. LME three-month copper dropped 3% to $14,329.50 per ton while COMEX prices fell 4.7%, narrowing the spread to near zero or negative. COMEX stocks reached a record 696,259 metric tons after months of tariff-driven inflows. Read →
Copper falls on White House tariff hesitation report.
Reuters · Thu, Sep 10, 9:12 PM ET
Three-month copper on the LME fell 3.1% to $14,312 per ton after hitting a record $14,875 earlier Thursday following the Reuters report. COMEX October futures slid 4.2% as the tariff premium eroded. The metal had gained 16% this year on inventory shifts ahead of potential duties. Read →
Iron Ore & Steel
What's moving · Iron ore futures extend fall below CNY 720/t as Chinese steel mill profitability drops to 8% and blast furnace rates slip.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
94.7 | -1.8% -1.7 |
-5.9% | -1.0% | -11.1% |
| Rebar SHFE $/mt |
396 | -0.9% -4 |
+0.6% | +2.3% | -45.0% |
| HRC SHFE $/mt |
428 | -1.7% -7 |
+3.7% | +4.1% | -43.5% |
Iron ore heads for steepest weekly loss since June on weak China margins.
Bloomberg · Thu, Sep 10, 2026
Singapore iron ore futures fell nearly 3% this week to as low as $96.40/t, erasing a Tuesday rebound. Steel mill margins deteriorated with only around 8% of Chinese mills profitable, the lowest since September 2024, while hot metal output stayed seasonally weak. The drop signals softer near-term demand for the steelmaking ingredient. Read →
Iron ore futures fall below CNY 720/t on weakening China steel margins.
TradingView News · Fri, Sep 11, 2026
Dalian and SGX iron ore futures extended losses for a third session below CNY 720 per ton. Only 8% of Chinese mills remained profitable, down from 30% weekly and 60% a year earlier, squeezed by high coke prices. CMRG reportedly advised mills to avoid Rio Tinto’s Pilbara Blend amid contract talks. Read →
Seaborne iron ore falls as China blast furnace rates drop to 89.08%.
Rio Times Online · Fri, Sep 11, 2026
Mysteel’s SEADEX 61% Fines index dropped US$1.25/dmt to US$97.35 on Thursday. China’s blast furnace operating rate fell 0.48 percentage points week-on-week to 89.08%, with daily pig iron output down 5,200 mt to 2.4028 million mt. Rio Tinto shares fell 4.19% while Vale slipped 1.04%. Read →
Precious Metals
What's moving · Gold holds near $4,330/oz as hot US PPI and oil above $100/bbl lift Fed rate-hike odds, pressuring the complex.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold | 4,386 | -0.5% -21 |
+1.4% | +20.2% | +144.7% |
| Silver | 64.49 | -0.7% -0.44 |
-8.0% | +52.1% | +171.5% |
| Platinum | 1,803 | +0.1% +2 |
-11.4% | +28.1% | +88.3% |
| Palladium | 1,314 | +1.5% +19 |
-19.3% | +6.9% | -36.7% |
Global gold ETFs add record $18B inflows in August
World Gold Council / Kitco News · Tue, Sep 9, 2026
Global gold ETFs recorded $18 billion in net inflows for August, the second-largest monthly total on record, pushing holdings to a record 4,189 tonnes and AUM to $615 billion. North America and Europe led with $7.7 billion and $7.9 billion respectively, reflecting renewed institutional allocation amid higher gold prices and portfolio diversification needs. Read →
BMI cuts 2026 platinum and palladium forecasts on weaker auto demand
MINING.COM · Wed, Sep 10, 2026
BMI lowered its 2026 platinum average price forecast to $1,900/oz from $2,000 and palladium to $1,400/oz from $1,500, citing softer car sales and faster-than-expected recovery in South African mine output. The firm still projects deficits for both metals this year but notes platinum’s longer-term structural support from industrial uses. Read →
Rare Earths & Critical Minerals
What's moving · China's looming Nov. 10 export controls on rare earth tech and equipment tighten supply chains for non-Chinese refiners and magnet makers.
China Nov controls test ex-China rare earth refining
Sebastian Evelyn · Fastmarkets · Wed, Sep 10, 2026
China's suspended October 2025 export controls on additional rare earth elements, equipment, and technology are set to resume November 10 unless extended. The measures would require licenses for foreign products using Chinese rare earth tech or materials above thresholds, hitting separation, alloy, and magnet production outside China. Ex-China dysprosium oxide prices reached $1,250 to 1,675/kg versus $270 to 330/kg in China, boosting Lynas and other non-Chinese producers but raising input costs. Read →
Lindian, Carester plan Kazakhstan rare earth separation plant
Staff Report · The Astana Times · Wed, Sep 10, 2026
Lindian Resources and Carester agreed to advance an 8,000 tpa solvent extraction and oxide separation facility in Stepnogorsk, Kazakhstan, with DFS due Q4 2026. The plant will produce separated NdPr oxides and mixed heavy rare earth compounds including dysprosium, terbium, and yttrium from Lindian's SARECO feedstock. Carester secured a 10-year offtake for 70% of output plus RoFR, supplying its French Caremag refinery. Read →
Maaden, MP Materials form Saudi rare earth JV
Global Mining Review · Wed, Sep 10, 2026
Saudi Maaden signed a binding term sheet with MP Materials and US Department of War backing for a rare earth refining and separation JV in Saudi Arabia. MP and DoW target 49% equity with Maaden holding at least 51%, using MP technical expertise and Saudi/global feedstock. The facility aims to diversify permanent magnet supply chains beyond China dominance. Read →
Shipping & Freight
What's moving · Houthi capture of Yemen's Mocha port and control of Bab el-Mandeb chokepoint drives tanker and container rates higher amid plunging transits through Hormuz and Red Sea.
Houthis seize Mocha, pushing oil above $105 as Bab el-Mandeb tightens
Fareed Rahman · The National · Thu, Sep 10, 2026
Houthi forces captured Yemen's Mocha port near Bab el-Mandeb, tightening control over a strait handling 10% of global oil supplies. Brent rose 4.12% to $105.40 per barrel. The move compounds Hormuz disruptions, heightening supply risks for Saudi exports to Asia. Read →
Ship transits through Bab el-Mandeb and Hormuz plunge sharply
Fareed Rahman · The National · Thu, Sep 10, 2026
Bab el-Mandeb crossings fell to six vessels on Thursday from 30 the prior day after Houthis seized Mocha. Hormuz transits dropped to nine commodity vessels on Wednesday, with many sailing dark. Kpler data shows sharp reductions in oil and dry-bulk movements through both chokepoints. Read →
Environment
What's moving · EU Parliament backs higher MSR threshold, curbing invalidation and easing supply pressure on EUAs.
EU Parliament seeks higher MSR invalidation threshold.
Bloomberg · Thu, Sep 10, 2026, 4:15 AM ET
The European Parliament’s environment committee voted to amend the Commission’s MSR proposal, keeping the invalidation mechanism but raising its threshold to 650 million allowances from March 2027 instead of scrapping it outright. This maintains a larger buffer of surplus EUAs in the reserve rather than permanently removing them. The change signals a more cautious approach to tightening supply ahead of broader ETS reforms, supporting modest upward pressure on EUA prices amid political negotiations. Read →
CCAs dip below $33; WCAs hit two-year lows post-auction.
Carbon Pulse · Fri, Sep 11, 2026
California Carbon Allowance futures fell below the $33 mark while Washington Carbon Allowances plunged to mid-$40s lows after weaker-than-expected Q3 auction results. The WCAs cleared under $40 in the auction, triggering a nearly 20% drop in futures from prior secondary market levels. The results highlight softening demand signals in the linked WCI markets ahead of potential further linkage developments. Read →
Real-World Assets & On-Chain Commodities
What's moving · Hyperliquid oil perps hit 500% annualized funding as shorts pay longs amid oil above $100.
SEC proposes transfer-agent overhaul for tokenized securities
Krisztian Sandor · CoinDesk · Thu, Sep 10, 5:01 PM ET
The SEC proposed overhauling its transfer-agent rules for the first time in about 40 years, explicitly allowing blockchain ledgers to serve as the official ownership record for securities. The change would eliminate the need for duplicate off-chain registers, cutting reconciliation costs and legal uncertainty for tokenized assets. Comments are due in early November. Read →
Arya.ag tokenizes $2B grain deposits on Avalanche
Omkar Godbole · CoinDesk · Thu, Sep 10, 5:42 AM ET
Arya.ag, India’s largest agricultural warehousing firm, launched a dedicated Avalanche L1 blockchain to tokenize grain deposits, warehouse receipts and loan status covering about $2 billion in stored crops. Lenders gain verifiable on-chain proof of collateral for roughly $1.3 billion in annual agricultural loans. Three major banks are preparing to join the network. Read →
Hyperliquid oil perps hit 500% funding as shorts pay longs
Protos · Thu, Sep 10, 2:56 PM ET
Hyperliquid’s WTI and Brent oil perpetuals printed deeply negative hourly funding rates, forcing short sellers to pay longs up to 500% annualized amid one-sided positioning. Oil rallied above $100 per barrel on geopolitical tensions, amplifying the skew. The extreme rates coincide with a futures contract roll on TradeXYZ HIP-3 markets. Read →
Industry News
Corporate & Deals
What's moving · Enbridge buys Tallgrass crude assets for $2.55B; Baker Hughes lifts 2026 guidance post-Chart deal.
Enbridge buys Tallgrass crude assets for $2.55B
Reuters · Wed, Sep 9, 4:57 PM ET
Enbridge agreed to acquire Blackstone-owned Tallgrass Energy's crude oil business for $2.55 billion in cash. The deal adds a 75% stake in the 460,000 bpd Pony Express Pipeline linking Rockies production to Cushing, plus Powder River Gateway stakes, 8.4 million barrels of storage, and marketing assets. It expands Enbridge's U.S. liquids network and is expected to be accretive to distributable cash flow per share. Read →
Tamarack, Headwater merge in $7.2B Clearwater deal
Reuters · Tue, Sep 8, 9:20 AM ET
Tamarack Valley and Headwater Exploration agreed to an all-stock merger valued at C$10 billion ($7.25 billion), creating the largest pure-play producer in Alberta's Clearwater oil play. Headwater shareholders receive one Tamarack share per share; the combined entity targets over 80,000 boepd run-rate production across 1,500+ sections with plans for a 20% dividend increase. Read →
Shell sells RI gas plant to Constellation for $715M
Reuters · Thu, Sep 10, 7:35 PM ET
Shell Energy North America agreed to sell its Rhode Island State Energy Center gas-fired plant (609 MW) to Constellation Energy for $715 million while acquiring 100% of Hunlock Creek Generating (169 MW gas-fired) in Pennsylvania. The moves reposition Shell's U.S. power portfolio toward the PJM market amid data-center-driven demand growth. Read →
Copart acquires ACV Auctions for $1.9B
Reuters · Thu, Sep 9 (time unknown)
Copart agreed to acquire peer ACV Auctions in an all-cash deal valued at about $1.9 billion. The transaction marks Copart's entry into dealer-to-dealer wholesale remarketing of vehicles. Read →
Regulation & Government
What's moving · US Treasury to sanction large bank Monday to tighten Iran energy financing squeeze amid surging oil prices.
US to sanction large bank Monday targeting Iran financing.
Jasper Ward · Reuters · Thu, Sep 10, 4:43 PM ET
Treasury Secretary Scott Bessent said the US will sanction an unnamed large bank on Monday as part of escalating pressure on Iran to end the six-month conflict. The move follows Operation Economic Outcast sanctions on nearly 60 entities and broadens secondary sanctions on sectors including shipping and gold. It targets financial intermediaries facilitating Iranian oil exports and revenues. Read →
UK adds Iran sanctions on energy, metals, gold from Sept 29.
Washington Trade & Tariff Letter · Fri, Sep 11
The UK will impose additional sanctions on Iran’s energy, metals, gold and software sectors starting Sept. 29. Restrictions extend to related shipping, insurance and banking activity. The measures build on existing designations and aim to further restrict Tehran’s commodity trade channels. Read →
China to ease export controls on metals, lift US ag tariffs.
Brett Fortnam · Inside U.S. Trade · Fri, Sep 11
China agreed to relax export controls on gallium, germanium, graphite and antimony and lift retaliatory tariffs on US agricultural products. The deal also allows Nexperia semiconductor products to leave China. It follows talks between Presidents Trump and Xi earlier in the week. Read →
Trump bans some Canadian alcohol, dairy, motorcycles effective Sept 29.
Washington Trade & Tariff Letter · Fri, Sep 11
President Trump signed proclamations banning certain Canadian alcoholic beverages, dairy products and large motorcycles from Sept. 29. The US also revised products subject to 50% Section 338 tariffs and removed some items from prior lists. Actions respond to Canada’s Sept. 8 retaliatory tariffs on $20 billion of US goods. Read →
What traders and commodity market feeds are talking about
Smoke spotted near Saudi pipeline; 7M bbl risk cited
X / multiple traders · Thu, Sep 10
Satellite imagery shows a large smoke plume near Saudi Arabia's East-West pipeline south of Medina. Traders on X, including shipping analysts, warn it could mean damage in multiple spots and take significant supply offline for weeks, amplifying Middle East risks. Read →
WTI jumps above $102 amid pipeline and conflict risks
X / multiple traders · Thu, Sep 10
WTI crude climbed more than 7% to above $102/bbl with Brent near $108 as traders price in ongoing geopolitical supply disruptions. Discussions highlight potential for further spikes if pipeline issues or shipping attacks escalate. Read →
Traders warn 7M bbl offline if pipeline hit confirmed
X / multiple traders · Thu, Sep 10
A trader highlighted unconfirmed reports of damage in at least eight places on the Saudi pipeline, potentially removing 7M bbl/day from global supply. The post sparked concern in #OOTT circles over prolonged outages. Read →
Gold sells off while oil surges on supply risks
X / multiple traders · Thu, Sep 10
Gold fell over 2% as the crude surge and potential rate-hike implications took center stage. Traders noted the inverse move amid inflation worries from higher energy prices. Read →
Houthis threaten Saudi Red Sea exports; oil watchers alert
X / multiple traders · Thu, Sep 10
Traders discussed Houthi advances along the Yemeni coast and risks to Saudi oil flows through the Red Sea. The conversation ties into broader supply concerns driving the crude rally. Read →
Recent video and podcast calls from respected oil and commodity analysts
Oil rally not transient amid China bid.
Jeff Currie on CNBC The Exchange (YouTube) · Thu, Sep 10
People are starting to go this is not transient. Watch/Listen →
Crude to $105 to 107; copper to $15,500.
Kunal Shah (Nirmal Bang) on CNBC-TV18 · Wed, Sep 9
Crude oil prices could rise to $105-$107 per barrel in the near term. Watch/Listen →
Brent tops $100 amid supply fears.
Bloomberg Open Interest (Bloomberg) · Tue, Sep 9
Bloomberg Open Interest covers Brent above $100 on Middle East supply concerns. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
Hormuz traffic returns to normal by December 31
20%
-6pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed rate hike in 2026
78%
+15pp w/w
Source: Polymarket
Hurricane Season 2026
US Gulf Coast hurricane landfall risk for upstream NG + oil supply. Polymarket odds, last 7 days.
Any Cat 4+ hurricane US landfall before 2027
6%
-10pp w/w
Source: Polymarket
Pandemic Watch
Tail-risk demand shock for jet fuel, gasoline, LNG. WHO general + named-pathogen probabilities. Polymarket odds, last 7 days.
Source: Polymarket
Was this forwarded to you? Subscribe free →
Hedge smarter, not harder.
This newsletter is brought to you by BoxWood · The AI-powered programmatic hedge booking system for commodity producers, consumers, refiners, hedge funds, and trading houses. See a live demo →
Morgan Downey's Commodity News is published by ComCurv, Inc. Curated and rewritten from public sources; every story links to its original publisher. Informational only · not financial, investment or trading advice.
Unsubscribe · View in browser · Subscribe
Unsubscribe · View in browser · Subscribe