The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Street views · Archive
Thursday, September 17, 2026
▶ The 2-minute market brief · video · 1.25x
Listen · the 2‑minute market briefToday's markets in two minutes. Tap to play
Prefer audio only? Listen here.
Markets at a glance
Last price as of Thu, Sep 17, 5:35 AM ET · 1-day change vs prior settle. Continuous front-month futures. Click price for news.
Today's sponsor slot is open. Ask us about it →
Downey's Take
Brent $105, down around $1 (-1%) and WTI $102 on Saudis offering additional crude to Asian buyers via ship-to-ship transfers off Oman’s Sohar port, reducing immediate tightness from the 7-day old East-West pipeline outage (had carried 5 million bpd, 4% global supply). That pipeline outage remains the key story. Partial pipeline flows could resume in days (bypassing damaged sections) with fuller restoration in weeks. Trump-Xi summit scheduled for this day week Thurs Sep 24, 2026, at the White House. First meeting since May in Beijing. Watching for any signal of US-China coordination on Iran.
Copper up $205/mt (+1.4%) on broader base metals rebound following weeks long sell offs and long-term demand expectations from data centers and renewables.
Tin up $547/mt (+1.1%) and Lead up $22 (+1.0%), both on spot market gains amid broader base metals strength.
Coffee down $2.8 (-1.0%) on strong Brazilian exports and favorable weather for the next crop pressuring prices.
Palladium down $12 (-0.9%) on post-Fed rate hike pressure on precious metals.
Kicker: Goldman Sachs long copper, short aluminum (Dec27) on mine supply constraints for copper versus Chinese overseas supply growth for aluminum.
Copper up $205/mt (+1.4%) on broader base metals rebound following weeks long sell offs and long-term demand expectations from data centers and renewables.
Tin up $547/mt (+1.1%) and Lead up $22 (+1.0%), both on spot market gains amid broader base metals strength.
Coffee down $2.8 (-1.0%) on strong Brazilian exports and favorable weather for the next crop pressuring prices.
Palladium down $12 (-0.9%) on post-Fed rate hike pressure on precious metals.
Kicker: Goldman Sachs long copper, short aluminum (Dec27) on mine supply constraints for copper versus Chinese overseas supply growth for aluminum.
Drivers and the Kicker trade idea are sourced from third-party news and bank or desk commentary. Informational only, not BoxWood trade advice.
The marquee commodity stories of the day
Oil falls as Saudis fix pipeline, easing supply fears
Bloomberg · Wed, Sep 16, 2026
Oil extended its biggest drop in more than six weeks on signs of easing Middle East supply disruptions. Saudi Arabia is seeking to return about half the capacity of its damaged East-West pipeline within days and full operations in about six weeks. Read →
LNG prices may spike on low EU stocks, Hormuz risks
Reuters · Thu, Sep 17, 2026
Global LNG prices could shoot higher this winter as Europe holds its lowest stocks in years and North Asian buyers face increased competition with the Strait of Hormuz still closed. Spot prices may reach $40/MMBtu if winter is colder than normal, per Woodmac. Read →
Physical oil cargoes top $130 on Saudi pipeline hit
Reuters · Tue, Sep 15, 2026
Prices for some physical oil cargoes in Europe jumped above $130 a barrel as buyers sought alternatives after Saudi Arabia cancelled cargoes and suspended loadings at Yanbu following East-West pipeline attacks. North Sea Forties hit $136.75. Read →
Oil rises on Saudi pipeline outage and new attacks
Reuters · Tue, Sep 15, 2026
Oil prices climbed as attacks left Saudi Arabia’s East-West pipeline offline and Houthis launched fresh strikes on Saudi sites. The outage threatens up to 4% of global supply while Hormuz traffic stays very low. Read →
Oil futures rise on Middle East supply disruption fears
Anthony Harrup · Wall Street Journal · Mon, Sep 15, 2026
Oil futures rose amid pessimism about Middle East flows after the Saudi East-West pipeline outage and heightened Houthi threats to Red Sea shipping. With multiple routes exposed, the market is pricing a broader loss of route flexibility. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 4US Natural Gas 3Wet Gas, NGLs/LPGs & Petchems 4Global Nat Gas & LNG 4Power 2Coal 1Agriculture 3Base Metals 4Iron Ore & Steel 3Precious Metals 2Rare Earths & Critical Minerals 2Shipping & Freight 2Environment 1Real-World Assets & On-Chain Commodities 3Corporate & Deals 5Regulation & Government 4Social buzz 5Watch & Listen 4Prediction Markets
Markets News
Oil
What's moving · Saudi pipeline repair timeline and Oman reroutes ease supply fears, sending Brent and WTI down over $1 each.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude | 101.94 | -0.5% -0.49 |
+77.5% | +60.3% | +41.6% |
| Brent | 104.93 | -0.9% -0.90 |
+72.4% | +55.5% | +39.2% |
| RBOB Gasoline | 3.518 | +0.9% +0.033 |
+90.7% | +61.7% | +49.8% |
| Heating Oil | 5.096 | -2.9% -0.151 |
+130.2% | +108.6% | +120.9% |
| NY RBOB Crk $/bbl |
45.82 | +4.3% +1.88 |
+128.6% +25.78 |
+64.9% +18.03 |
+71.9% +19.17 |
| NY HO Crk $/bbl |
112.07 | -5.0% -5.85 |
+215.3% +76.53 |
+187.3% +73.06 |
+350.7% +87.20 |
| NY 321 Crack $/bbl |
67.90 | -1.0% -0.70 |
+169.4% +42.69 |
+115.4% +36.37 |
+160.6% +41.84 |
Saudi Oman reroutes blunt pipeline outage impact, oil falls.
Reuters · Thu, Sep 17, 2026
Saudi Arabia offered more crude loadings to Asian refiners via ship-to-ship transfers off Oman’s Sohar port after attacks shut its East-West pipeline and suspended Yanbu loadings. Brent fell $1.24 (1.2%) to $104.59/bbl and WTI $1.14 (1.1%) to $101.29/bbl, extending Wednesday’s $3+ drop. The moves partially offset lost Red Sea exports while Hormuz traffic stayed low. Read →
Brent settles 2.7% lower at $105.83 after supply fears ease.
Farhan Rafid and Anthony Harrup · Dow Jones / Morningstar · Wed, Sep 16, 2026
Brent settled down 2.7% at $105.83/bbl and WTI lost 3.2% to $102.43/bbl, retreating from four-month highs. EIA reported a 640k bbl U.S. crude draw (smaller than expected) while gasoline and distillate stocks built; European refiners paid record premiums for Johan Sverdrup crude as Saudi delays hit Red Sea flows. Read →
API shows 7.1M bbl U.S. crude build, pressuring prices.
CNBC / Reuters sources · Wed, Sep 16, 2026
API data indicated a 7.1M bbl U.S. crude inventory build for the week ended Sept. 11 versus expected 1.6M bbl draw, with gasoline and distillate also rising. Brent fell 0.86% to $107.82/bbl and WTI 0.92% to $104.86/bbl even as Yanbu loadings remained suspended after the East-West pipeline attack. Read →
Aramco to restore half pipeline capacity in days.
LiveMint / Bloomberg sources · Thu, Sep 17, 2026
Aramco aims to return about half the East-West pipeline capacity within days via bypass work after drone attacks shut the line on Sept. 10. Full restoration is eyed in about six weeks; the outage had forced European cargo cancellations and prompted Asian reroutes via Oman. Read →
US Natural Gas
What's moving · Late-summer heat drives record September power burn, lifting Henry Hub futures toward $3 despite ample storage.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub | 2.894 | +0.1% +0.003 |
-21.5% | -1.5% | -43.3% |
Late heat fuels record Sept power burn
Chris Newman · Natural Gas Intelligence · Wed, Sep 16, 2026
Natural gas power burn across the Lower 48 started September at its strongest pace on record as summer-like heat lingered over the South. Power burn ran 13% above the five-year average, expanding Henry Hub premiums in the Southeast and pointing to a lighter-than-normal injection in the upcoming EIA storage report. The heat supports near-term demand while the season advances. Read →
Futures push higher but stall short of $3
Chris Newman · Natural Gas Intelligence · Wed, Sep 16, 2026
Natural gas futures moved up early Wednesday on record-challenging Southern heat and firm demand but faded as LNG feedgas softened and forecasts turned bearish beyond the weekend. October hovered below $3 resistance while Golden Pass LNG feedgas rebounded. Traders await Thursday’s EIA storage report. Read →
Enbridge opens season for new Permian pipeline
Natural Gas Intelligence · Wed, Sep 16, 2026
Enbridge launched a non-binding open season for its proposed West Texas Express system to move up to 2 bcfd of Permian natural gas to El Paso markets. The project targets rising associated-gas output from the basin amid growing LNG and power demand. It adds to a wave of Permian takeaway expansions planned through 2027. Read →
Your ad here
One sponsor per issue, and nobody else
This is where a sponsor's block sits: room to actually say what you do, to the people who read this letter every morning.
Email us for the audience and the rates →
Wet Gas, NGLs/LPGs & Petchems
What's moving · US propane inventories posted a counterseasonal 1.4 MMbbl draw, eroding the surplus ahead of winter heating season.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.250 | +0.7% +0.002 |
+5.5% | -0.8% | -35.0% |
| Propane C3 $/gal |
0.846 | +2.3% +0.019 |
+37.2% | +18.8% | -33.6% |
| N-Butane NC4 $/gal |
1.264 | +1.7% +0.021 |
+69.6% | +40.9% | -13.7% |
| Isobutane IC4 $/gal |
1.454 | +2.4% +0.033 |
+87.0% | +57.5% | +0.9% |
| Pentane C5 $/gal |
2.049 | +2.4% +0.047 |
+74.8% | +55.7% | +21.1% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 6 | unch | +7 | unch | +1 |
| C3 Frac Sprd ¢/gal | 58 | +2 | +30 | +14 | -23 |
| C2 vs NWE Naph $/mt | -659 | +13 | -355 | -290 | -281 |
| C3 vs NWE Naph $/mt | -412 | +22 | -246 | -218 | -401 |
| C5 as % WTI | 84 | +2 | -1 | -3 | -14 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
EIA propane stocks · week ending Fri, Sep 11
A 1.4 mb draw took US propane stocks to 109.1 mb, 19.9 mb (22%) above the five-year average and 10.2 mb above a year ago. Exports ran 2,213 kb/d (+253 kb/d w/w) against production of 2,973 kb/d.
US stocks 109.1 mb -1.4 mb w/w | Year ago 98.9 mb | 5-yr avg 89.2 mb |
Gulf Coast 69.6 mb PADD 3 | Midwest 26.3 mb PADD 2 | Exports 2,213 kb/d +253 kb/d w/w |
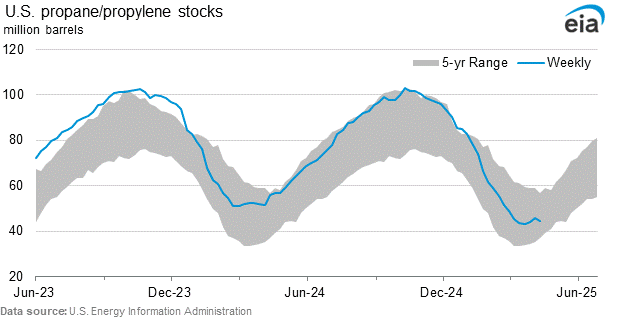
Source: EIA Weekly Petroleum Status Report · Full EIA report →
US propane stocks post counterseasonal 1.4 MMbbl draw
RBN Energy · Wed, Sep 16, 2026
US propane/propylene inventories fell 1.4 MMbbl in the latest EIA week, a counterseasonal draw that trims the record surplus. Stocks remain historically high but continued draws or sub-normal builds could tighten balances ahead of winter heating demand. The move reflects stronger export pull and product supplied outpacing seasonal norms. Read →
Wolf Midstream advances $500M Alberta NGL Phase Three
ER Velasco · The Deep Dive · Wed, Sep 16, 2026
Wolf Midstream reached final investment decision on Phase Three of its NGL North system, adding 0.6 Bcf/d of gas processing and lifting NGL capacity to 110,000 bpd including over 80,000 bpd ethane. The expansion includes a third de-ethanizer, unit-train rail terminal ramp to 60,000 bpd, and cogeneration; most output is backed by long-term fixed-fee contracts with investment-grade counterparties and is slated for 2027 service. Read →
Wolf FID $500M NGL North Phase Three expansion
BOE Report · Wed, Sep 16, 2026
Wolf Midstream announced FID on a $500 million Phase Three expansion of its proprietary NGL North system in Alberta with CPP Investments backing. The project boosts processing by 0.6 Bcf/d, adds de-ethanization and rail loading capacity, and targets 110,000 bpd NGL output (80,000+ bpd ethane) under mostly contracted fixed-fee terms; core construction is already underway with phased online dates from late 2026 into 2028. Read →
US propane inventories fall to 109.1 MMbbl week ending Sep 11
The Fill Line / EIA · Wed, Sep 16, 2026
EIA data for the week ending Sep 11 shows US propane and propylene primary stocks at 109.1 million barrels, down from the prior week and 10.3% above the five-year median. The decline aligns with the counterseasonal draw reported by RBN, signaling early erosion of the elevated inventory position built through summer. Read →
Global Nat Gas & LNG
What's moving · TTF holds near €78/MWh as EU storage lags at 68% full, curbing injections amid Gulf LNG disruptions.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
77.58 | -0.6% -0.45 |
+175.5% | +135.4% | +19.2% |
| Dutch TTF $/MMBtu |
26.10 | -0.6% -0.15 |
+175.5% | +135.4% | +19.2% |
| JKM $/MMBtu |
27.23 | – | +183.4% | +136.2% | +8.9% |
EU gas storage · gas day Tue, Sep 15
EU gas storage is 68.7% full, 777 TWh in store, 16.0 points below the five-year average for this date and 12.2 points below a year ago. Germany, the bloc's largest store, is 56.0%.
EU full 68.7% +0.17 pts d/d | Year ago 80.8% | 5-yr avg 84.7% same date |
Germany 56.0% |
Source: GIE AGSI+ · Full AGSI+ data →
Asia LNG imports hit 8-year Sept low as prices deter buyers
Reuters · Thu, Sep 17, 2026
Kpler data show Asia LNG arrivals at 20.09 million tons in September, the weakest since 2018, as spot prices reached $26/mmBtu. Europe is pulling more cargoes with September imports rising to 7.98 million tons, easing its storage pressure. The shift frees supply for northwest Europe amid Qatar disruptions but keeps TTF elevated. Read →
Asia LNG demand to drop 3 to 10% this year on high prices
Reuters · Thu, Sep 17, 2026
Analysts forecast Asian LNG demand falling 3 to 10% year-on-year due to prices doubling to $26/mmBtu after Gulf supply cuts from the Iran conflict. China leads the decline with a projected 6.1 million ton drop. Lower Asian buying supports Europe by redirecting flexible cargoes, sustaining TTF strength. Read →
EU gas storage at record low 67 to 68% full for season
EUToday · Thu, Sep 17, 2026
EU storage sits around 67 to 68% full, 16 points below the five-year average, the lowest seasonal level in years. Executives at Gastech noted the shortfall leaves Europe exposed ahead of winter as Hormuz disruptions limit Qatar LNG. Storage is projected to reach only 75% by November even with higher imports. Read →
TTF holds above €80/MWh near 2022 highs on storage woes
Michael Kern · OilPrice.com · Wed, Sep 16, 2026
Front-month TTF rose 0.3% to around €80.55/MWh ($92.95 equivalent) amid low storage and Middle East supply risks. Prices have held above €80/MWh after a 6% Monday jump, the highest since the 2022 crisis. Low inventories and Gulf LNG constraints keep the market tight. Read →
Power
What's moving · PJM files FERC backstop auction to fill 6.8 GW capacity shortfall driven by data-center load growth.
PJM seeks FERC approval for backstop auction to close 6.8 GW shortfall
Utility Dive · Tue, Sep 16, 2026
PJM Interconnection filed a proposal at FERC on Friday for a one-time reliability backstop auction running Sept. 30 to Oct. 21 to procure capacity and address a 6.8 GW shortfall from its prior base auction. The shortfall stems primarily from surging data-center and large-load demand forecasts outpacing new supply additions. PJM also proposes facilitating bilateral deals between data centers and generators, with costs allocated pro rata to zones and a proposed $555/MW-day price cap. Read →
US House passes bill requiring data centers to pay full grid upgrade costs
AFP · Wed, Sep 17, 2026
The US House of Representatives passed the bipartisan Ratepayer Protection Act 417 to 3, directing state utility regulators to ensure data centers bear the full costs of new power generation, transmission, and grid upgrades needed to serve them. The measure responds to voter concerns over rising electricity bills linked to AI-driven data-center demand, including in PJM where such load has driven billions in added capacity costs. The bill now moves to the Senate. Read →
Coal
What's moving · India thermal plant coal stocks hit critical levels at 66 plants amid surging power demand.
New Hope declares highest dividend since 2022
Reuters · Tue, Sep 15, 2026
New Hope Corp declared a 30 Australian cent final dividend, its largest in four years, despite FY net profit falling 63% to A$161 million. Shares rose over 4% to multi-year highs on expectations that tighter supply and higher realized prices will support returns. The company exceeded production guidance with saleable output up 7.6% as thermal coal markets tighten. Read →
Agriculture
What's moving · Soybean futures rise near 3-year highs on China buying ahead of Trump-Xi talks; grains mixed on harvest, weather.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn | 535 | +0.1% +1 |
+21.5% | +26.3% | +1.5% |
| Wheat | 728 | -0.3% -3 |
+43.6% | +38.9% | +2.8% |
| Soybeans | 1,326 | +0.4% +6 |
+28.7% | +27.8% | +3.3% |
| Sugar | 18.78 | -0.6% -0.11 |
+25.1% | +22.1% | -2.1% |
| Coffee | 278.8 | -1.0% -2.8 |
-20.1% | -27.8% | +48.8% |
| Cocoa | 5,971 | -0.1% -8 |
-1.5% | -17.4% | +124.1% |
| Cotton | 83.89 | -0.6% -0.47 |
+30.7% | +28.8% | -10.0% |
Soybeans climb on China buying, Trump-Xi talks ahead
Reuters / Business Recorder · Thu, Sep 17, 2026
US soybean futures rose Thursday with the most-active CBOT contract up 0.74% near $13.30/bushel, near a three-year high. China has passed the halfway mark on its 25 million metric ton annual US soybean purchase commitment from the Busan summit. Traders watch US Treasury Secretary Scott Bessent's weekend meeting with China's He Lifeng ahead of next week's Trump-Xi summit; rain delaying Midwest harvest and a smaller Canadian wheat crop added support. Read →
Grains mixed: soybeans up, corn down, wheat gains
Anthony Harrup · Dow Jones / Morningstar · Wed, Sep 16, 2026, 4:40 PM ET
December wheat settled up 0.3% at $7.3075/bushel on the CBOT. November soybeans rose 0.1% to $13.205/bushel while December corn fell 0.3% to $5.3425/bushel. Statistics Canada cut 2026 Canadian wheat production 11% year-over-year to 36.1 million metric tons; Brazil's Conab raised 2026/27 corn output to 148 million metric tons and soybeans to 181.6 million tons. Read →
China hits halfway on 25M ton US soybean pledge
Bloomberg · Sun, Sep 14, 2026
China's state-owned traders booked at least 1 million tons of US soybeans last week, bringing total purchases for the season near 13 million tons, more than half of the 25 million-ton annual target through 2028. The buying comes ahead of President Xi Jinping's planned visit to Washington and follows a mid-2026 agreement easing some tariffs on US farm goods. Read →
Base Metals
What's moving · Copper rises as China Yangshan import premium hits $118/t, highest in nearly four years.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
14,555 | +1.4% +205 |
+17.3% | +45.4% | +55.5% |
| Copper SHFE $/mt |
14,262 | +0.6% +84 |
+12.3% | +44.1% | +49.5% |
| Aluminium SHFE $/mt |
3,194 | +0.3% +9 |
+7.3% | +24.5% | +10.1% |
| Zinc SHFE $/mt |
3,445 | -0.2% -5 |
+14.7% | +25.3% | +12.9% |
| Nickel SHFE $/mt |
16,210 | +0.8% +130 |
-4.3% | +6.7% | -21.1% |
| Lead SHFE $/mt |
2,110 | +1.0% +22 |
-4.2% | +1.2% | +3.5% |
| Tin SHFE $/mt |
52,719 | +1.1% +547 |
+25.5% | +55.4% | +54.2% |
Copper rises on China demand signals, Yangshan premium at $118/t.
Reuters · Wed, Sep 16, 2026
LME three-month copper rose 0.7 to 1.1% to around $14,188-$14,231 per tonne on signs of active Chinese buying. The Yangshan premium jumped 7% to $118 per tonne, its highest in nearly four years, as buyers restock after a price dip. BNP Paribas noted the move eases prior tightness while LME spreads shifted into contango. Read →
Copper rebounds as Yangshan premium climbs to $118/t high.
Finimize · Wed, Sep 16, 2026
LME copper climbed about 1.1% to near $14,237 per tonne amid firmer Chinese import appetite. The Yangshan premium rose to $118 per tonne, the strongest level in almost four years, signaling restocking by Chinese buyers. COMEX-LME premium narrowed and inflows to US warehouses slowed amid ongoing US tariff uncertainty. Read →
Alba aluminium output at 80% of pre-war levels amid disruptions.
Tom Daly · Reuters · Wed, Sep 16, 2026
Aluminium Bahrain (Alba) CEO said the smelter operates at 80% of pre-Iran war capacity, or 1.3 million tonnes per year from lines 4 to 6. Exports route via Jeddah and Sohar after Strait of Hormuz issues; alumina arrives by 300 to 350 daily truckloads. Full 1.6 million tonne capacity return depends on raw materials and regional stability. Read →
Lithium Argentina closes $180m Ganfeng convertible note deal.
INN / Mining Weekly · Wed, Sep 16, 2026
Lithium Argentina closed a $180 million strategic investment from Ganfeng Lithium via a six-year 4% unsecured convertible note convertible at $12.50 per share. Proceeds plus cash will repay $259 million in notes due January 2027, strengthening the balance sheet for Caucharí-Olaroz Stage 2 and PPG project integration. Ganfeng stake rises to 16.1% on full conversion. Read →
Iron Ore & Steel
What's moving · CISA self-discipline pledge and pre-holiday restocking lift DCE iron ore 0.35% to 711 yuan while SGX holds below $100.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
93.8 | +0.2% +0.2 |
-6.9% | -2.0% | -12.0% |
| Rebar SHFE $/mt |
406 | +0.1% +0 |
+3.0% | +4.7% | -43.7% |
| HRC SHFE $/mt |
438 | +0.1% +1 |
+6.4% | +6.7% | -42.1% |
DCE iron ore rises 0.35% to 711 yuan on holiday buying.
Reuters · Thu, Sep 17, 2026
Dalian iron ore futures climbed 0.35% to 711 yuan per tonne as mills booked seaborne cargoes ahead of October National Day holidays, with Mysteel data showing a 43% jump in transactions. SGX October futures edged 0.26% higher to $96.05, remaining below $100. Analysts noted tumbling mill margins may limit further restocking and output gains. Read →
Rebar and HRC futures edge higher on Shanghai exchange.
Reuters · Thu, Sep 17, 2026
Shanghai Futures Exchange rebar rose 0.1% and hot-rolled coil 0.24% alongside iron ore gains. Coking coal and coke also advanced over 1%. Weak underlying steel demand from construction persists despite the short-term buying surge. Read →
Baowu considers 15 to 25% Jimblebar stake from BHP.
Reuters · Thu, Sep 4, 2026
China Baowu, the world’s largest steelmaker, is exploring a 15 to 25% stake in BHP’s Jimblebar mine, which produced 62.5 million tonnes for BHP in FY2026. The interest comes amid ongoing contract tensions and could deepen Chinese influence over major Pilbara supply. Read →
Precious Metals
What's moving · Fed's first rate hike since 2023 and hawkish dot plot drive gold lower to $4,270/oz after three-session drop.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold | 4,351 | -0.8% -37 |
+0.2% | +18.3% | +148.4% |
| Silver | 64.46 | -0.7% -0.46 |
-8.1% | +54.5% | +189.1% |
| Platinum | 1,783 | -0.2% -3 |
-12.4% | +27.6% | +91.2% |
| Palladium | 1,302 | -0.9% -12 |
-20.1% | +11.4% | -34.3% |
Gold holds decline after Fed raises rates, tilts hawkish
Bloomberg · Wed, Sep 16, 11:54 PM ET
The Federal Reserve raised its benchmark rate by 25 basis points for the first time in three years and signaled another hike likely before year-end via its median dot plot at 4.1%. Gold fell 2% over three sessions to around $4,270/oz as higher yields increase the opportunity cost of holding non-yielding bullion. The move followed sticky inflation and elevated oil prices, pressuring precious metals broadly. Read →
Gold and silver slip after Fed hike and hawkish signal
Anshul · CNBC TV18 · Wed, Sep 16, 10:14 PM ET
COMEX gold fell 0.88% to $4,348.90/oz and silver 0.90% to $64.335/oz on Thursday following the Fed's unanimous 25 bp hike and projections for further tightening. The decision shifts focus to yields and the dollar as headwinds for non-yielding metals. Oil's decline provided some relief but did not offset the hawkish policy tilt. Read →
Rare Earths & Critical Minerals
What's moving · US government funding surges for domestic rare earth separation and magnet capacity amid China export risks.
USA Rare Earth inks $1.6B US gov't LOI for mine-to-magnet buildout
Global Mining Review · Wed, Jan 28, 2026
USA Rare Earth secured a non-binding LOI from the US Department of Commerce for up to $1.6 billion in CHIPS Act support, including $277 million in direct funding and a $1.3 billion loan, plus DOE collaboration on heavy REE separation. The package targets Round Top mine development, heavy REE processing including dysprosium and terbium, and expanded NdFeB magnet capacity to 10,000 tpy. It accelerates US friend-shoring of permanent-magnet supply chains critical for defense and semiconductors. Read →
Ucore gains extra $4.6M DoW funds to add Sm and Gd separation
Jackson Chen · Mining.com.au · Mon, Sep 15, 2026
Ucore Rare Metals received a $4.6 million OTA modification from the US Department of War, bringing total Pentagon funding for its RapidSX technology to $27 million. The expansion adds samarium and gadolinium separation capabilities at the Louisiana Strategic Metals Complex for defense and aerospace magnets. Both elements face high supply risk from China's export controls and were prioritized in US government assessments. Read →
Shipping & Freight
What's moving · Yanbu crude loading halt since Sep 11 spikes VLCC rates to records amid Hormuz/Red Sea disruptions.
US Gulf-China VLCC lump sum hits record $44.8M
Bloomberg · Wed, Sep 16, 2026
Baltic Exchange data shows the cost to charter a VLCC for 2 million barrels from the US Gulf Coast to China reached a record $44.8 million on Tuesday, up from $39 million the prior day. The surge stems from Middle East supply disruptions and tanker scarcity as buyers secure alternative barrels; Kpler data indicates six VLCCs are slated for October USGC-Asia loadings. Pre-war levels stood near $17.8 million. Read →
Hormuz transits fall to four, no VLCCs or LNG
Reuters · Wed, Sep 16, 2026
Preliminary Kpler ship-tracking data recorded just four commodity vessel transits through the Strait of Hormuz on Tuesday, down from seven and well below the 10-day average of 18. No VLCCs or LNG carriers transited; movements included one VLGC with LPG and one Panamax tanker with naphtha, both exiting via dark routes. Attacks in the region continue to suppress traffic while Bab el-Mandeb saw 22 transits. Read →
Environment
What's moving · EU nations back 121 million extra free ETS permits for heavy industry, easing carbon costs by €8.25 billion.
EU backs 121m extra free ETS permits for industry
Kate Abnett · Reuters · Wed, Sep 16, 2026
EU member states endorsed a plan granting heavy industry an additional 121 million free CO2 allowances for 2026 to 2030 under the ETS, exceeding the European Commission's July proposal. The move targets chemical, metals, ceramics and glass producers and could save firms €8.25 billion in compliance costs. Negotiations with Parliament are fast-tracked for a 2026 deal amid broader ETS reform talks due in 2027. Read →
Real-World Assets & On-Chain Commodities
What's moving · Anchorage Digital custody for tokenized uranium and Tether's $1.5B gold lending drive RWA commodity momentum.
Anchorage adds custody for tokenized uranium on Etherlink
Cointelegraph / crypto.news · Wed, Sep 16, 2026
Anchorage Digital Bank, the first federally chartered U.S. crypto bank, added institutional custody support for Etherlink (Tezos L2) assets including xU3O8, a token backed by physical uranium concentrate held by Cameco under UK-law trust. The $9M market-cap token now sits in segregated bank accounts alongside stablecoins and wrapped assets, enabling institutions to hold tokenized uranium with the same controls as other digital holdings and settle transfers in minutes rather than weeks. Read →
Tether provides $1.5B in gold financing to U.S. dealer
Bloomberg · Wed, Sep 16, 2026
Tether accounted for the bulk of Gold.com Inc.'s $1.7B in outstanding precious-metals leases as of end-June, with $1.45B owed to the stablecoin issuer after Tether took a stake earlier this year. The financing, at a 1.75% annual lease rate, lets Tether monetize its 146-ton physical gold hoard while supplying low-cost liquidity to the U.S. bullion dealer, deepening crypto-native capital's role in physical gold markets. Read →
Payward eyes U.S. Hyperliquid perps via Bitnomial
CoinDesk · Wed, Sep 16, 2026
Kraken parent Payward announced plans to offer U.S. clients onchain perpetual futures on Hyperliquid’s blockchain via its CFTC-regulated Bitnomial exchange and clearinghouse, starting with HIP-3 permissioned markets and subject to regulatory approval. The structure would route client accounts through NinjaTrader Clearing while keeping execution on Hyperliquid’s public chain, marking the first regulated U.S. on-ramp for the platform’s commodity and other RWA perps. Read →
Industry News
Corporate & Deals
What's moving · DNO revises $396M all-cash takeover of Capricorn Energy; National Fuel Gas weighs $5B gas unit options; Continental signs Venezuela oil MOU.
DNO revises Capricorn takeover to all-cash $396M deal
Prerna Bedi · Reuters · Thu, Sep 17, 6:52 AM ET
UK-listed Capricorn Energy agreed to revised all-cash terms for DNO's $396 million takeover, with DNO offering $5.214 cash per share after dropping a dividend component. The deal gives DNO entry into Egypt's upstream while outbidding Genel Energy, amid rising Middle East-focused M&A as higher oil prices support consolidation. Read →
National Fuel Gas explores $5B sale or spinoff of gas unit
David French · Reuters · Wed, Sep 16, 4:29 PM ET
National Fuel Gas is reviewing strategic options for its Seneca Resources natural gas production and midstream assets, potentially valued at around $5 billion. Options include full/partial sale, merger, or spinoff, advised by Goldman Sachs, to focus on its regulated utility business amid AI-driven power demand. Read →
Continental Resources signs Venezuela oil MOU with PDVSA
Sumit Saha · Reuters · Wed, Sep 16, 4:46 PM ET
Continental Resources signed an MOU with PDVSA to operate and develop the Ayacucho 2 block in Venezuela's Orinoco Belt, with 30 billion barrels of resource in place across 126,000 acres. The company plans a production-sharing agreement soon and 100% working interest, with first output possible in 18 months. Read →
Ghana Gas sets early 2027 FID for $500M pipeline
Reuters · Wed, Sep 16, 4:55 PM ET
State-owned Ghana Gas plans a final investment decision by early 2027 on a 278-km $500 million West-East onshore gas pipeline to supply industries in the southeast from its western processing plant. The government would take a 30% stake, with the rest privately funded, to meet rising demand and reduce reliance on shared regional pipelines. Read →
BKV closes Barnett shale upstream/midstream/CCS deal
World Oil · Wed, Sep 16
BKV Corp. completed its acquisition of Barnett Shale assets, adding over 65 MMcfe/d production (over 50% liquids), 0.35 Tcfe PDP reserves, 117,000 net acres, 1,000 wells, midstream infrastructure, and an operated CCS project that captured over 100,000 metric tons of CO2 recently. The deal strengthens BKV's position in the basin. Read →
Regulation & Government
What's moving · US House passes Russia sanctions-tariff bill targeting oil buyers, sending it to Trump for signature.
House passes Russia sanctions-tariff bill 262 to 159.
Patricia Zengerle · Reuters · Wed, Sep 16, 6:37 PM ET
The US House approved the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 by 262 to 159, authorizing President Trump to impose up to 100% tariffs on top buyers of Russian oil and gas including China and India. The bill also imposes new sanctions on Russian officials, oligarchs, financial institutions and the shadow fleet, plus extends Iran sanctions. It heads to Trump for signature after Senate passage last month. Read →
House clears bill for Trump tariffs on Russia oil buyers.
Bloomberg · Wed, Sep 16, 10:42 PM ET
Congress approved legislation granting Trump authority to levy tariffs up to 100% on countries purchasing significant Russian petroleum products. The measure, backed by Ukrainian officials, overcomes business lobby opposition over expanded tariff powers. It now goes to the president who is expected to sign it. Read →
USDA releases biofuels trade plan after record exports.
USDA · Wed, Sep 16
The USDA issued its American Biofuels Trade Outlook to expand ethanol and renewable diesel exports following 2025's record 2.2 billion gallons shipped worth $4.7 billion. The plan targets removal of foreign restrictions on crop-based biofuels, especially EU limits, and pushes E10 blending in Latin America and Asia. It supports US farmers by increasing global demand for corn and soybean feedstocks. Read →
Russia bans sulfuric acid exports to year-end.
Interfax · Mon, Sep 14
Russia's government imposed a temporary export ban on sulfuric acid effective within 10 days of publication and running through December 31, 2026. The measure protects domestic supplies for mineral fertilizer producers and industrial users. Exceptions require prime ministerial approval or apply to transit and intergovernmental deals; Kazakhstan is the main prior buyer. Read →
What traders and commodity market feeds are talking about
Traders assess Saudi pipeline recovery pace and oil supply impact
X / multiple traders · Thu, Sep 17
Oil traders on X under #OOTT are closely tracking calculations around a potential 40% recovery of Saudi Arabia's East-West pipeline flows, with analysts estimating it could allow about 1 mbd in crude exports while balancing domestic needs. Discussions highlight bottlenecks like pumps and turbines that could delay full restoration beyond initial headlines, keeping physical market tightness in focus as inventories continue drawing. This matters as any slower recovery sustains the supply deficit and supports elevated prices. Read →
India flags US sanctions bill threat to energy trade
X / @staunovo · Thu, Sep 17
Commodity analyst Giovanni Staunovo highlighted India's warning that a US bill targeting buyers of Russian oil could damage New Delhi-Washington relations and disrupt global energy markets. Traders note this adds geopolitical layers to already strained supply routes, with potential ripple effects on crude flows and pricing. The post drew engagement from energy watchers emphasizing the political risks in the oil trade. Read →
Dubai crude at $123.70 amid tight physical market
X / @FluxOfficials · Thu, Sep 17
The Officials reported Dubai crude assessed at $123.705/bbl with a physical premium of $28.965/bbl on Sep 17, alongside Unipec declaring three Murban cargos to major traders. #OOTT participants view this as evidence of persistent physical tightness despite any paper market pullbacks. It underscores strong demand for Middle East grades amid broader supply concerns. Read →
Singapore stocks climb as traders watch flows
X / @staunovo · Thu, Sep 17
Giovanni Staunovo noted Singapore oil product inventories increased by 2.172mb to 42.638mb last week. #OOTT traders are monitoring this alongside other regional data for signs of easing or persistent tightness in the products market. Rising stocks could signal shifting balances if crude supply issues persist. Read →
Yaroslavl refinery fire out post-drone attack
X / multiple traders · Thu, Sep 17
Traders shared updates that a fire at Russia's Yaroslavl oil refinery, hit by a Ukrainian drone attack, has been put out according to the regional governor. #OOTT conversations link this to ongoing energy infrastructure risks in the Russia-Ukraine conflict, adding to global supply volatility concerns. The incident highlights continued threats to refining capacity. Read →
Recent video and podcast calls from respected oil and commodity analysts
Oil above $100 amid new supply risks
Scott Modell, Rapidan Energy Group CEO on BNN Bloomberg · Wed, Sep 16
New supply risks keep oil above $100 heading into midterms. Watch/Listen →
BofA flags $150 oil if infrastructure hit
Brent could reach $150 if Saudi East-West pipeline hit permanently. Watch/Listen →
Saxo pod on oil, copper and grains
Oil shock reshapes commodity rally as yields surge and metals retreat. Watch/Listen →
Hansen sees gold potentially at $6k in 2027
Gold could revisit $5,600 and touch $6,000 in 2027 on structural demand. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
Hormuz traffic returns to normal by December 31
17%
+1pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed rate hike in 2026
Resolved: Yes
Source: Polymarket
Hurricane Season 2026
US Gulf Coast hurricane landfall risk for upstream NG + oil supply. Polymarket odds, last 7 days.
Source: Polymarket
Pandemic Watch
Tail-risk demand shock for jet fuel, gasoline, LNG. WHO general + named-pathogen probabilities. Polymarket odds, last 7 days.
Source: Polymarket
Was this forwarded to you? Subscribe free →
Hedge smarter, not harder.
This newsletter is brought to you by BoxWood · The AI-powered programmatic hedge booking system for commodity producers, consumers, refiners, hedge funds, and trading houses. See a live demo →
Morgan Downey's Commodity News is published by ComCurv, Inc. Curated and rewritten from public sources; every story links to its original publisher. Informational only · not financial, investment or trading advice.
Unsubscribe · View in browser · Subscribe
Unsubscribe · View in browser · Subscribe