The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Street views · Archive
Friday, October 9, 2026
▶ The 2-minute market brief · video · 1.25x
Listen · the 2‑minute market briefToday's markets in two minutes. Tap to play
Prefer audio only? Listen here.
Markets at a glance
Charts: grey is the prior session, color is today.
Last price as of Fri, Oct 9, 5:34 AM ET · 1-day change vs prior settle. Continuous front-month futures. Click price for news.
Today's sponsor slot is open. Ask us about it →
Downey's Take
Crude down on Trump signaling productive Iran talks and no US attack before US midterms on Nov 3, easing immediate supply disruption fears after Thursday's $5 surge on Hormuz tanker attacks, the heaviest tanker attacks since the war began Feb 28.
Trackers put about 9, 12 strikes on tankers in and around Hormuz in the week through early October, a record for the conflict) and US Gulf Hurricane Isaias crude shut-ins of 1.3mb/d.
Despite Trumps statement about US midterms on Nov 3, Israel may attack Iran ahead of its own Oct 27 elections, two and a half weeks from now.
Propane up $0.039 (+4.2%) on downstream restocking and cost support from elevated Saudi CP prices amid tight Middle East LPG supply.
Tin down $2120 (-3.9%) on stronger US dollar and bearish positioning pressuring base metals after post-holiday demand check.
N-Butane up $0.057 (+3.8%) on geopolitical cost support and downstream demand.
Platinum up $55 (+3.3%) on lower US Treasury yields and softer oil easing inflation and rate concerns.
Pentane up $0.068 (+3.2%) on crude-linked energy sector strength.
Trackers put about 9, 12 strikes on tankers in and around Hormuz in the week through early October, a record for the conflict) and US Gulf Hurricane Isaias crude shut-ins of 1.3mb/d.
Despite Trumps statement about US midterms on Nov 3, Israel may attack Iran ahead of its own Oct 27 elections, two and a half weeks from now.
Propane up $0.039 (+4.2%) on downstream restocking and cost support from elevated Saudi CP prices amid tight Middle East LPG supply.
Tin down $2120 (-3.9%) on stronger US dollar and bearish positioning pressuring base metals after post-holiday demand check.
N-Butane up $0.057 (+3.8%) on geopolitical cost support and downstream demand.
Platinum up $55 (+3.3%) on lower US Treasury yields and softer oil easing inflation and rate concerns.
Pentane up $0.068 (+3.2%) on crude-linked energy sector strength.
Drivers and the Kicker trade idea are sourced from third-party news and bank or desk commentary. Informational only, not BoxWood trade advice.
The marquee commodity stories of the day
Copper eyes weekly gain on China restock, mine risks
Bloomberg · Thu, Oct 8, 2026
Copper futures rose as much as 1.3% on the London Metal Exchange Friday, heading for a weekly gain. Low inventories in top consumer China after its national holiday point to restocking, while a gauge of import demand hit a four-year high and a possible supply disruption looms at a Chilean mine. Read →
Oil jumps as Hormuz tanker attacks slow flows
Financial Times · Thu, Oct 8, 2026
Oil prices jumped as tanker attacks by Iran increased and flows through the vital Strait of Hormuz fell sharply after rising close to 90% of prewar levels last month. The renewed shipping squeeze adds to supply worries amid the ongoing Middle East conflict. Read →
Hormuz ship transits hit two-month low after attacks
Reuters · Wed, Oct 7, 2026
The number of vessels transiting the Strait of Hormuz fell to the lowest in more than two months. Attacks on tankers reached their highest level last week since the start of the US-Israeli war with Iran, per shipping data. Read →
Cheap coal vs expensive gas spurs coal export surge
Reuters · Fri, Oct 9, 2026
Australian thermal coal export prices are around 80% cheaper than LNG delivered to Asia, the widest discount in four years. Utilities in the region are expected to ramp up coal imports for winter heating amid high LNG costs. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 4US Natural Gas 2Wet Gas, NGLs/LPGs & Petchems 4Global Nat Gas & LNG 3Power 3Coal 1Agriculture 4Base Metals 4Iron Ore & Steel 3Precious Metals 2Rare Earths & Critical Minerals 3Shipping & Freight 2Environment 3Real-World Assets & On-Chain Commodities 2Corporate & Deals 2Regulation & Government 4Social buzz 5Watch & Listen 4Prediction Markets
Markets News
Oil
What's moving · Oil retreats after Trump rules out Iran strikes before midterms, easing supply fears despite Gulf tanker attacks and US hurricane shut-ins.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude | 90.51 | -1.1% -0.98 |
+57.7% | +53.7% | +12.4% |
| Brent | 102.93 | -1.3% -1.35 |
+69.2% | +64.1% | +23.0% |
| RBOB Gasoline | 3.300 | -0.5% -0.016 |
+93.5% | +81.3% | +38.8% |
| Heating Oil | 4.830 | -1.1% -0.053 |
+128% | +119% | +92.1% |
| NY RBOB Crk $/bbl |
48.09 | +0.6% +0.31 |
+238% +33.87 |
+174% +30.52 |
+148% +28.72 |
| NY HO Crk $/bbl |
112.35 | -1.1% -1.24 |
+255% +80.70 |
+233% +78.66 |
+347% +87.23 |
| NY 321 Crack $/bbl |
69.51 | -0.3% -0.21 |
+247% +49.48 |
+203% +46.57 |
+227% +48.22 |
Oil falls as Trump pauses Iran strikes pre-midterms
Bloomberg · Fri, Oct 9, 2026
Brent eased below $103/bbl and WTI near $91 after Trump posted that the US would not attack Iran before midterms, citing productive discussions and record Hormuz flows excluding Iranian barrels. The move followed Thursday's 4%+ surge driven by tanker attacks and Gulf production cuts. US sanctions on Iranian shipping networks remain in force. Read →
Oil settles lower after IEA accelerates stock releases
Reuters via Business Recorder · Wed, Oct 8, 2026
Brent closed down 38 cents at $100.20/bbl and WTI fell $1.16 to $88.28/bbl as the IEA agreed to speed up releases of up to 100 million barrels, prioritizing diesel. US crude stocks drew 3.2 million barrels to 424.1 million in the week to Oct 2, beating expectations for a build. France plans to release 10 million barrels of diesel from reserves. Read →
Iran, Houthis escalate Hormuz tanker, Saudi strikes
Wall Street Journal · Fri, Oct 9, 2026
Iranian and Houthi attacks on tankers in the Strait of Hormuz and Saudi targets including Riyadh airport lifted oil prices sharply. Gulf producers continue using US-protected convoys and ship-to-ship transfers despite elevated risks and insurance costs. Brent settled at $104.27/bbl, up 4.1%, with WTI at $91.87/bbl. Read →
Gulf producers battle to regain market share post-war
Reuters · Wed, Oct 8, 2026
Saudi, UAE and Iraq crude exports exceeded pre-war averages near 18 million bpd in the week to Oct 3 as Hormuz traffic recovered, per Kpler. Global supply deficit is forecast to narrow to 250,000 bpd in October from 4 million bpd in May. Brent remains above $100/bbl as shipping attacks and high freight rates persist. Read →
US Natural Gas
What's moving · Hurricane Isaias Gulf shutdowns and sub-79 bcf storage build lift November futures to two-week high near $3.28.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub | 3.133 | -1.1% -0.035 |
-15.0% | +0.9% | -41.4% |
EIA gas storage · week ending Fri, Oct 2
A 85 Bcf injection took working gas to 3,500 Bcf, 68 Bcf (2%) above the five-year average and 130 Bcf below a year ago.
Working gas 3,500 Bcf +85 Bcf w/w | Year ago 3,630 Bcf | 5-yr avg 3,432 Bcf |
Consensus – this week | Year-ago chg +80 Bcf | 5-yr avg chg +99 Bcf |
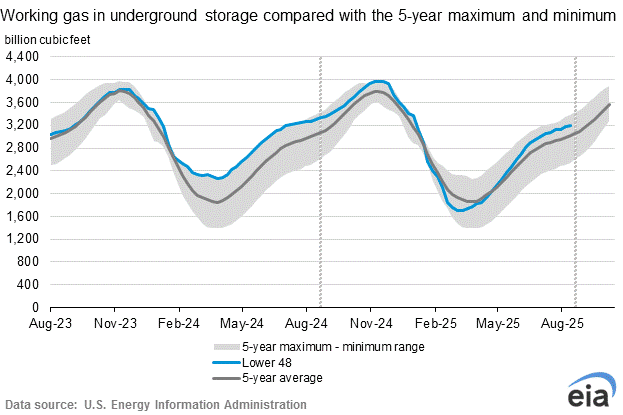
Source: EIA Weekly Natural Gas Storage Report · Full EIA report →
Natgas futures climb 2% to two-week high on Gulf outages, demand forecasts.
Reuters · Thu, Oct 9, 2026
November Henry Hub futures rose 7.4 cents or 2.3% to $3.277/MMBtu, the highest close since Sept. 24 and fifth straight gain. Lower-48 output fell toward 108.5 bcfd on Gulf of Mexico pipeline reductions ahead of Hurricane Isaias plus earlier Appalachian and Texas force majeures; LSEG raised this week's demand forecast. The move came ahead of the EIA storage print and despite expectations of a below-average injection. Read →
EIA storage rises 85 bcf to 3,500 bcf, above 79 bcf consensus.
Energy Edge Consulting · Thu, Oct 8, 2026
Working gas in Lower-48 storage reached 3,500 bcf after an 85 bcf injection for the week ended Oct. 2, exceeding the 79 bcf analyst median and leaving stocks 68 bcf above the five-year average but 130 bcf below year-ago levels. Production pulled back sharply to 107.4 bcfd with Isaias weighing on offshore volumes; LNG feedgas was also lower at Freeport and Cove Point. Read →
Your ad here
One sponsor per issue, and nobody else
This is where a sponsor's block sits: room to actually say what you do, to the people who read this letter every morning.
Email us for the audience and the rates →
Wet Gas, NGLs/LPGs & Petchems
What's moving · Mont Belvieu propane jumps 4.2% to 97.2¢/gal on export rebound and Gulf Coast stock draw.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.283 | +2.0% +0.005 |
+19.3% | -0.5% | -35.3% |
| Propane C3 $/gal |
0.972 | +4.2% +0.039 |
+57.6% | +44.0% | -33.5% |
| N-Butane NC4 $/gal |
1.568 | +3.8% +0.057 |
+110% | +85.6% | -1.7% |
| Isobutane IC4 $/gal |
1.740 | +3.2% +0.054 |
+124% | +99.1% | +8.8% |
| Pentane C5 $/gal |
2.167 | +3.2% +0.068 |
+84.9% | +68.9% | +14.7% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 8 | +1 | +8 | unch | -1 |
| C3 Frac Sprd ¢/gal | 69 | +4 | +41 | +30 | -29 |
| C2 vs NWE Naph $/mt | -681 | -28 | -376 | -359 | -275 |
| C3 vs NWE Naph $/mt | -394 | -12 | -226 | -204 | -411 |
| C5 as % WTI | 101 | +4 | +15 | +9 | +2 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
ONEOK and MPLX JV for 400 Mb/d Texas City LPG export terminal
Oil & Gas Journal · Tue, Oct 7, 2026
ONEOK and MPLX formed a 50/50 JV, Texas City Logistics, to build a 400,000 b/d LPG export terminal in Texas City, Texas, plus a 24-inch pipeline from ONEOK's Mont Belvieu storage to the terminal. The $1.4 billion terminal, slated for early 2028 startup with MPLX operating it, targets low-ethane propane and normal butane; each partner reserves 200 Mb/d. ONEOK will own 80% of the $350 million pipeline. The projects expand Gulf Coast export optionality for NGLs from Mont Belvieu and Permian sources. Read →
Energy Transfer expands Nederland NGL export terminal
Tanks and Terminals · Thu, Oct 8, 2026
Energy Transfer announced expansion at its Nederland NGL Export Terminal, adding 240 Mb/d ethane export capacity (100% contracted long-term to 2040s) and 55 Mb/d LPG capacity. The project includes expanded Mont Belvieu-to-Nederland pipeline capacity, two new ship docks, and previously announced storage tank expansions (propane and butane tanks to 1.2 MMbbl and 0.8 MMbbl by 1H27). Phased startup begins 2028; total Nederland refrigerated NGL export capacity will exceed 1.25 MMb/d post-docks, lifting ET's system total to 1.7 MMb/d with Marcus Hook. Read →
Targa adds Speedway NGL pipeline and Yeti plant in Permian
VettaFi / Advisor Perspectives · Thu, Oct 9, 2026
Targa Resources announced the Speedway NGL Pipeline (initial 500 Mb/d, expandable to 1 MMb/d, 500 miles, $1.6 billion, in-service 3Q27) from Permian assets to Mont Belvieu, plus the Yeti gas processing plant (275 MMcf/d). Buffalo Run residue-gas interconnect is also advancing. These support Targa's wellhead-to-water strategy amid Permian volume growth and raise 2026 growth capex guidance; Speedway addresses near-capacity existing NGL takeaway while adding downstream fractionation and export flexibility. Read →
EIA propane stocks build as exports weaken
RBN Energy · Wed, Oct 7 or recent weekly
EIA data showed a larger-than-expected 1.8 MMbbl build in total U.S. propane/propylene stocks for the week ended Sept 25, reaching 109.6 MMbbl (record Gulf Coast PADD 3 at 70.4 MMbbl). The build followed a sharp export decline; inventories remain 17 to 19% above five-year averages heading into seasonal draw. Recent weeks saw rebounding exports pulling stocks lower from prior peaks, tightening the prompt market and supporting Mont Belvieu prices amid strong international demand. Read →
Global Nat Gas & LNG
What's moving · TTF rises on historically low EU storage at 72 to 73% and ENTSOG winter outlook flagging LNG reliance amid geopolitical risks.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
77.21 | -2.1% -1.64 |
+174% | +140% | -9.4% |
| Dutch TTF $/MMBtu |
25.40 | -2.1% -0.54 |
+174% | +140% | -9.4% |
| JKM $/MMBtu |
25.95 | +0.3% +0.08 |
+170% | +135% | -21.5% |
EU gas storage · gas day Wed, Oct 7
EU gas storage is 73.1% full, 828 TWh in store, 15.0 points below the five-year average for this date and 9.7 points below a year ago. Germany, the bloc's largest store, is 59.4%.
EU full 73.1% +0.15 pts d/d | Year ago 82.9% | 5-yr avg 88.1% same date |
Germany 59.4% |
Source: GIE AGSI+ · Full AGSI+ data →
ENTSOG: EU storage at 72% Oct 1, winter supply secure but LNG critical
ENTSOG · Thu, Oct 8, 2026
EU underground gas storage stood at 72% full on Oct 1 after a challenging injection season, the lowest on record for the date. ENTSOG's outlook says infrastructure can meet winter demand under base cases but warns storage could drop below 30% by March without strong LNG inflows; continued injections and monitoring urged. Low stocks heighten reliance on global LNG amid volatile prices from Middle East disruptions. Read →
EU gas operators: 72% storage historically low but infrastructure ready
AFP / Yahoo Finance · Thu, Oct 8, 2026
ENTSOG states Europe can meet winter gas demand despite storage at historically low 72% on Oct 1 versus 83% a year earlier. LNG import capacity can offset weaker stocks, but limited availability risks stocks below 30% by winter's end. Continued early-winter injections and monitoring needed; storage varied widely, e.g., 85% in France vs 59% in Germany. Read →
JKM futures hit record volumes on tenders and TTF-JKM spreads
Hellenic Shipping News / ICE data · Thu, Oct 9, 2026 (or recent)
JKM LNG monthly futures saw record trading volumes driven by tender activity and sharp inter-hub spreads, with JKM-TTF arb moves prompting hedging. Colder European weather expectations widened spreads and supported prices despite LNG inflows. Activity concentrated in 2026 delivery months amid Northeast Asia heating-season positioning. Read →
Power
What's moving · FERC orders PJM and five other US grid operators to reform large-load tariffs for data centers amid surging AI demand.
FERC orders six US grid operators to reform large-load tariffs
Federal Energy Regulatory Commission · Thu, Oct 8, 2026
FERC issued show-cause orders under Section 206 of the Federal Power Act directing PJM, MISO, SPP, CAISO, ISO-NE and NYISO plus their transmission owners to justify or reform tariffs governing data-center and other large-load interconnections within 60 days. The orders target cost allocation, co-location with generation, flexible transmission service and speculative queue management to accelerate reliable integration while protecting ratepayers. The moves respond to the Secretary of Energy’s ANOPR and aim to deliver “speed to power” for AI-driven demand without shifting costs to existing customers. Read →
DOE urges PJM to shield ratepayers from data-center costs
Senior Reporter · Utility Dive · Thu, Oct 8, 2026
The Department of Energy filed a rare statement at FERC urging PJM to revise its reliability backstop procurement plan by Oct. 29 to prevent cost shifts from new data centers and large loads onto existing ratepayers. DOE said PJM should implement FERC-identified cost-allocation reforms and track whether projects enter service to assign generation costs to the responsible customers. The filing addresses PJM’s capacity shortfall driven by data-center forecasts after the grid operator failed to meet reserve margins in recent auctions. Read →
Texas pauses new data-center permits and queue reviews
TheMarketscafe / Reuters · Fri, Oct 9, 2026
Texas Gov. Greg Abbott directed the TCEQ to halt data-center permits and ordered an ERCOT audit of the 474 GW large-load interconnection queue, of which 90% are data centers. ERCOT delayed its Batch Zero study and will require developers of 25 MW+ projects to provide details on power demand, water use, ownership and local impacts by mid-October, with the audit targeted for completion around Dec. 10. The pause addresses reliability risks from load growth exceeding five times the state’s record peak demand. Read →
Coal
What's moving · Newcastle thermal coal at $143/t trades $20/MMBtu below Asian LNG, spurring Q4 export surge.
SAIL airlifts first Mongolian coking coal sample
Reuters · Wed, Sep 30, 10:56 AM ET
Steel Authority of India airlifted a 1-tonne Mongolian coking coal sample to test as an alternative to Australian supply. India imports 95% of its coking coal needs, with Australia providing at least half; imports are forecast to rise 3 to 5% in 2026/27. Logistics via Russia would add cost but aid diversification. Read →
Agriculture
What's moving · Wheat futures rally 3% on Russian frost damage to 15 to 30% of winter grains, while soy and corn sag ahead of USDA WASDE.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn | 502 | +0.2% +1 |
+13.9% | +21.4% | -5.9% |
| Wheat | 683 | +0.0% +0 |
+34.8% | +37.1% | -6.6% |
| Soybeans | 1,294 | +0.5% +6 |
+25.5% | +28.5% | +5.3% |
| Sugar | 20.25 | +0.5% +0.10 |
+34.9% | +25.8% | -0.4% |
| Coffee | 288.0 | -0.4% -1.1 |
-17.4% | -22.8% | +41.0% |
| Cocoa | 5,602 | -1.1% -63 |
-7.6% | -4.2% | +109% |
| Cotton | 80.85 | +1.1% +0.91 |
+25.4% | +26.3% | -26.6% |
Wheat surges 3% on Russian frosts; soy, corn ease pre-WASDE
Julie Ingwersen · Reuters · Fri, Oct 9, 2026
CBOT July wheat jumped 18.5 cents to $6.26 per bushel after Russia's grain union reported frosts damaging 15 to 30% of winter grains, far above ministry estimates. Soybeans fell 9 cents to $11.79 to 1/4 and corn dipped 1.25 cents to $4.50 to 1/2 as traders awaited Wednesday's USDA supply-demand reports. The wheat move reverses a nine-session slide fueled by harvest progress and prior oversold conditions. Read →
Australia wheat exports jump 47% on Black Sea hits
First Squawk / multiple wires · Fri, Oct 9, 2026
Australia is on track for 2.6 million tonnes of grain exports in October, 47% above the five-year average, with wheat comprising two-thirds of shipments. Escalating attacks on Black Sea ships and terminals disrupt Russian and Ukrainian flows, boosting demand from the Philippines, Indonesia and China. This marks Australia's busiest October for grain exports in 16 years and supports wheat prices. Read →
Raw sugar drops from 19-month high on profit-taking
Reuters · Fri, Oct 9, 2026
ICE raw sugar futures fell 1.9% to 20.44 cents per lb after hitting a 19-month peak of 21.24 cents on Wednesday. Traders viewed the El Nino-driven rally as overdone. Coffee and cocoa also declined, with Arabica pressured by high Brazilian exports and cocoa weighed by a growing 2025/26 global surplus estimated at 450,000 to 720,000 tonnes. Read →
Grains ease pre-WASDE as China soy stocks hit 15-year high
Rio Times Online · Fri, Oct 9, 2026
Grain trackers fell on Thursday with soybeans down 0.72%, corn off 0.47% and wheat lower 0.56% ahead of Friday's USDA WASDE. Chinese crushers held a record 7.96 million tonnes of soybeans in late September, covering needs through early February and cooling near-term U.S. export prospects. Markets also digested solid but below-average weekly export sales. Read →
Base Metals
What's moving · LME copper rebounds 1.2% on Centinela strike risk and China restocking after holiday; tin drops over 5%.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
14,702 | +1.5% +220 |
+18.4% | +37.5% | +52.4% |
| Copper SHFE $/mt |
14,663 | -0.5% -69 |
+15.5% | +37.3% | +53.6% |
| Aluminium SHFE $/mt |
3,115 | -0.3% -10 |
+4.7% | +19.3% | -0.9% |
| Zinc SHFE $/mt |
3,422 | -1.1% -40 |
+13.9% | +24.3% | +9.1% |
| Nickel SHFE $/mt |
15,775 | +0.4% +69 |
-6.9% | +4.1% | -19.7% |
| Lead SHFE $/mt |
2,139 | -0.2% -4 |
-2.9% | +1.2% | +7.2% |
| Tin SHFE $/mt |
51,811 | -3.9% -2,120 |
+23.3% | +46.5% | +35.3% |
Copper eyes weekly gain on China demand and Chile mine strike risk
Bloomberg via Livemint · Fri, Oct 9, 2026
LME three-month copper rose as much as 1.2% to $14,474.50/t Friday after China returned from its National Day holiday with low inventories signaling restocking needs. A strike at Antofagasta’s Centinela mine in Chile, one of the country’s largest, threatens output starting within two weeks and adds to supply risks. Copper is tracking for a roughly 1.5% weekly gain amid tariff uncertainty and seasonal demand. Read →
LME tin drops 5.22% to $51,447/mt as SHFE contract breaks below 390k yuan
Shanghai Metals Market (SMM) · Fri, Oct 9, 2026
LME tin fell $2,832/mt or 5.22% to $51,447/mt overnight on Oct 8, while the most-traded SHFE tin SN2610 contract dropped 4.50% in the night session below the 390,000 yuan mark. LME tin inventories hit a near three-year low at 4,310 mt after four straight days of declines. Macro pressures including Fed rate-hike expectations, strong dollar and surging oil prices drove the selloff despite tight ore supply from Myanmar and Indonesia. Read →
LME zinc falls 1.49% to $3,710/mt on macro pressure and position cutting
Shanghai Metals Market (SMM) · Fri, Oct 9, 2026
LME zinc closed down $59/mt or 1.49% at $3,710/mt after opening at $3,772/mt, briefly hitting $3,828.50/mt then dropping sharply as bulls cut positions. SHFE zinc 2611 contract fell 1.44% to 25,685 yuan/mt. LME zinc stocks declined 325 mt to 127,425 mt while Chinese regional inventories rose post-holiday. Read →
LME copper rises 1.16% to $14,475/t on mine risks and China import demand
Asharq Al-Awsat / Reuters · Fri, Oct 9, 2026
Three-month LME copper climbed 1.16% to $14,475/t, recovering from prior losses, as a strike at Antofagasta’s Centinela mine threatens November output and China’s Yangshan import premium hit $125/t, its highest since November 2022. Stocks outside the US remain tight after metal flowed to Comex ahead of potential tariffs. Other LME metals also gained, with zinc up 1.25%. Read →
Iron Ore & Steel
What's moving · DCE iron ore futures hit 18-month low at 682.5 yuan/mt as Chinese steel margins collapse and hot-metal output falls to six-month low of 2.34 Mt/day.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
90.4 | +0.3% +0.3 |
-10.2% | -7.5% | -12.1% |
| Rebar SHFE $/mt |
397 | +0.3% +1 |
+0.8% | +3.6% | -49.8% |
| HRC SHFE $/mt |
425 | +0.1% +0 |
+3.1% | +4.6% | -46.8% |
DCE iron ore hits 18-month low on weak steel margins
Reuters via Kitco News · Thu, Oct 8, 2026
DCE most-traded iron ore contract closed down 3.12% at 682.5 yuan/mt ($101.84/t), lowest since April 2025. Only 7% of Chinese steelmakers were profitable end-September; daily hot-metal output slid to six-month low of 2.34 Mt as mills start or plan maintenance. SGX November contract hit lowest since September 2024 at $90.95/t during holiday; excess supply and falling freight added pressure. Read →
Iron ore extends weekly drop on excess supply
Bloomberg · Fri, Oct 9, 2026
Iron ore futures headed for third straight weekly loss; SGX fell as much as 0.9% Friday to lowest since September 2024. Dalian contracts hovered near two-year lows after post-holiday resumption. Ample seaborne supply and subdued Chinese steel demand outlook weighed on prices despite trading resumption. Read →
China iron ore port stocks rise to 173.15 Mt
Mysteel · Fri, Oct 9, 2026
Inventories at 47 major Chinese ports reached 173.15 Mt as of Oct 8, up 963 kt week-on-week. Fines rose 701 kt and lumps 524 kt; daily port discharge averaged 3.58 Mt. Build reflects post-holiday arrivals amid softer mill buying as hot-metal output contracts. Read →
Precious Metals
What's moving · Gold rises over 1% on softer dollar, lower yields and oil as Fed hike bets ease.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold | 4,213 | +1.3% +56 |
-3.0% | +5.3% | +140% |
| Silver | 60.66 | +2.1% +1.23 |
-13.5% | +29.2% | +168% |
| Platinum | 1,697 | +3.3% +55 |
-16.6% | +6.0% | +68.8% |
| Palladium | 1,159 | +3.0% +34 |
-28.9% | -19.9% | -45.4% |
Gold rises over 1% on softer dollar and yields.
Ashitha Shivaprasad · Reuters · Fri, Oct 9, 2026
Spot gold rose 1.1 to 1.4% to around $4,177-$4,191/oz Friday after a two-month low Wednesday, with US futures up similarly. A breather in the dollar rally, slipping 10-year Treasury yields and lower oil prices after Trump ruled out an Iran attack before midterms supported prices. Traders price a low October hike chance but 83% odds for December amid ongoing inflation concerns. Read →
Global gold ETFs post record $31bn Q3 inflows.
World Gold Council · Fri, Oct 7, 2026
Physically backed gold ETFs attracted $10bn in September and a record $31bn in Q3 despite an 8.5% gold price drop that month. Holdings rose 67 tonnes to a record 4,256 tonnes while AUM fell 7% to $574bn. Europe led with $3.6bn in September (record $14bn quarter), followed by North America at $4bn ($12bn quarter), led by UK-listed funds. Read →
Rare Earths & Critical Minerals
What's moving · EU picks 46 strategic critical-minerals projects to cut China reliance.
EU selects 46 projects to speed critical minerals diversification
Julia Payne · Reuters · Fri, Oct 9, 8:05 AM ET
The European Commission selected 46 strategic raw material projects across 16 EU countries covering copper, lithium, nickel, cobalt, manganese, graphite, rare earths and others. The projects require around €21.1 billion in investment and receive faster permitting plus help accessing public and private funding under the Critical Raw Materials Act. The move aims to boost EU mining, processing and recycling capacity and reduce dependence on China for defense, automotive and renewable supply chains. Read →
US-China rare earth truce extended to Jan. 10 2027
Tobi Opeyemi Amure · The Street / AOL · Thu, Oct 8, 7:33 PM ET
Treasury Secretary Scott Bessent said the US and China extended their trade truce from Nov. 10 to Jan. 10 2027, giving more time to address economic issues including rare earth shipments. The extension keeps China's suspended October 2025 export controls on hold but leaves unresolved concerns over supply levels and licensing. Stocks of MP Materials, USA Rare Earth and Lynas face a tightened timeline as defense procurement rules tighten in 2027. Read →
Lynas buys Meteoric for A$968m Brazil rare earths deal
Lynas Rare Earths / Reuters · Thu, Oct 1 (recent coverage Oct 8 to 9)
Lynas Rare Earths agreed to acquire Meteoric Resources in an all-share deal valued at A$968 million to gain the Caldeira ionic clay project in Brazil. The deposit holds significant dysprosium-terbium reserves, giving Lynas its first major non-Chinese heavy rare earth feedstock source. The move strengthens Western supply options for high-performance permanent magnets ahead of potential tighter Chinese controls. Read →
Shipping & Freight
What's moving · VLCC rates hit record $1.4M/day on Gulf-East Asia as Hormuz shuttling ties up 40%+ of fleet.
BDI falls 0.7% to 2,973 on Capesize weakness.
Vedika Thorat · Reuters · Thu, Oct 8, 2026
The Baltic Dry Index fell 21 points or 0.7% to 2,973 Thursday, its lowest since August 25. Capesize earnings dropped $768 to $37,420 amid soft Chinese iron ore demand after the holiday. Panamax and supramax indexes edged higher. Read →
Transpacific spot rates peak as Golden Week looms.
WorldCargo News · Wed, Oct 8, 2026
Far East to US West Coast spot rates rose 1.4% to $8,346/FEU and East Coast 0.7% to $11,523/FEU on October 1 per Xeneta. The analyst sees the post-Hormuz peak but expects rates to stay elevated through year-end rather than collapse. Read →
Environment
What's moving · EUAs rebound above March trendline on late buying as UKAs hit 8-month high on EU-UK link optimism.
EUAs rebound above trendline; UKAs hit 8-month high on link hopes
Carbon Pulse · Thu, Oct 8, 5:09 PM ET
A late-session buying surge lifted EU allowance prices back above the March bullish trendline, reversing five days of weakness. UKA prices climbed to an eight-month high on optimism that the EU and UK will finalize a linking agreement next month. The moves highlight how policy linkage expectations are supporting near-term compliance prices in both markets. Read →
Virginia advances post-2026 RGGI rules for mid-October
Carbon Pulse · Thu, Oct 8
Virginia’s Department of Environmental Quality updated its post-2026 RGGI Model Rules to align with the Third Program Review. Regulations are slated for publication in mid-October. The step supports ongoing implementation after the state’s July 2026 return, which has coincided with higher allowance prices in recent auctions. Read →
CCAs drift toward $33 on long-term investor focus
Carbon Pulse · Thu, Oct 8
California Carbon Allowance benchmark futures edged higher toward $33 while Washington Carbon Allowance futures also rose, narrowing the spread between the contracts. Activity reflects investors positioning for longer-term supply tightness ahead of linkage effects and tighter budgets. The moves occur amid broader North American compliance market stability. Read →
Real-World Assets & On-Chain Commodities
What's moving · Dubai VARA renews RWA tokenization focus while Partners Group explores blockchain infrastructure and Kalshi files CFTC proposal for never-expiring WTI oil futures.
Dubai VARA renews tokenized-asset integration push
Riza Dagoc · TokenPost · Thu, Oct 8, 2026
Dubai’s Virtual Assets Regulatory Authority is prioritizing settlement infrastructure, real estate tokenization, and links between virtual assets and legal rights. The move follows an Oct. 6 reserve requirement for virtual-asset providers and aims to embed tokenized assets into existing financial and legal systems rather than treating them as isolated digital representations. Read →
Partners Group explores tokenized RWA infrastructure
John Kim · TokenPost · Wed, Oct 8, 2026
The $186 billion Swiss asset manager is examining blockchain infrastructure for tokenized real-world assets as institutions prepare broader market entry. Vincent Ng discussed practical utility and on-chain services with AssetoFinance executives, signaling preparation for tokenized private assets ahead of expected 2026 institutional adoption. Read →
Industry News
Corporate & Deals
What's moving · Devon sells Eagle Ford assets to Crescent for $4.2B as ONEOK closes Brazos Permian midstream buy and Cenovus agrees Athabasca oilsands takeover.
Devon sells Eagle Ford assets to Crescent for $4.2B cash.
Reuters · Thu, Oct 8, 2026
Devon Energy agreed to sell its Eagle Ford shale assets in South Texas, covering about 90,000 net acres and roughly 4% of its production or 68,000 boe/d, to Crescent Energy for $4.2 billion in cash. The deal, expected to close by year-end, lets Devon sharpen focus on the Permian after its Coterra merger while Crescent gains scale and over 600 Tier 1 locations adjacent to its operations with expected synergies near $100 million annually. Read →
ONEOK completes $4.425B Brazos Permian midstream acquisition.
ONEOK / GlobeNewswire · Tue, Oct 6, 2026
ONEOK closed its $4.425 billion cash acquisition of Brazos Midstream’s Permian Midland Basin natural gas gathering and processing assets. The deal more than doubles ONEOK’s Midland Basin processing capacity to about 2.3 Bcf/d, adds 700 miles of pipelines and 600,000 dedicated acres under long-term contracts, and is funded partly by a $9 billion Apollo minority equity investment. Read →
Regulation & Government
What's moving · China's planned 10 to 15% tariffs on US crude and LNG from Feb 10 drive commodity trade tensions.
Traders seek Beijing waivers on US crude, LNG tariffs
Reuters · Fri, Oct 9, 2026
Traders plan waiver requests after China announced 10% tariffs on US crude oil and 15% on LNG, effective February 10, in retaliation for recent US tariffs on Chinese goods. Several tankers carrying 6 million barrels of US WTI and ANS crude plus LNG vessels are en route; waivers are expected for booked cargoes but harder for new deals. The move will redirect US LNG flows to Europe and other Asian buyers while China boosts imports from Qatar and Russia. Read →
US sanctions 17 Iran shadow fleet vessels
Timothy Gardner and Daphne Psaledakis · Reuters · Thu, Oct 8, 2026, 4:58 PM ET
The US Treasury sanctioned individuals, networks and 17 vessels transporting Iranian crude, products and petrochemicals under Operation Economic Outcast to cut funding for Iran's war efforts, missiles and IRGC. Iran has roughly 20 million barrels of crude left at sea outside the blockade, with loading halted. Analysts say the impact is limited as most oil has already been delivered. Read →
Russia extends diesel export ban to Oct 31
Reuters · Wed, Sep 30, 2026
Russia extended its ban on diesel exports by producers through October 31 to protect domestic supplies amid refinery attacks. The curbs, in place since July, add pressure to global diesel markets already strained by Middle East and Ukraine conflicts and record US prices above $6.50/gallon. Russia is typically the second-largest diesel exporter after the US. Read →
CRS details ongoing US tariff actions 2026
Congressional Research Service · Thu, Oct 8, 2026
The CRS report outlines Trump administration tariffs including Section 301 forced-labor duties of 10 to 12.5% on 60+ economies effective July 2026 and Section 232 actions on aluminum, autos and other goods. It notes the Lindsey O. Graham Act's new authorities for up to 500% duties on Russian goods and 100% on top importers of Russian energy by October 19, 2026. Read →
What traders and commodity market feeds are talking about
Treasury hits Iran's shadow fleet, cutting oil export routes
X / multiple traders · Thu, Oct 8
US Treasury announced sanctions neutralizing most of Iran's shadow fleet used to export petroleum products. Traders on #OOTT are discussing the move's impact on global supply and potential retaliation risks amid ongoing Middle East tensions. Read →
JPM oil note sparks trader debate on Iran supply risks
X / @CRUDEOIL231 · Thu, Oct 8
Hedge fund PM posted JPMorgan's latest oil views with #OOTT and #iran tags. High engagement shows traders parsing bank forecasts against geopolitical headlines, with replies noting European energy impacts. Read →
Brent tops $104 as Iran strike talk and Hormuz fears rise
X / multiple traders · Thu, Oct 8
Traders cite reports of US planning strikes on Iran before midterms and tanker attacks in Strait of Hormuz. Discussions highlight underpriced escalation risk, with one noting potential for much higher prices if flows are disrupted. Read →
Isaias forces 25% Gulf offshore output offline
X / multiple traders · Thu, Oct 8
Storm adds to supply concerns as 500k bpd Gulf production halted. Combined with Middle East issues, traders note dual shocks tightening the market ahead of potential further disruptions. Read →
SPR draw slows; traders question demand and deals
X / @malhani_hamed · Thu, Oct 8
Analyst posts on slowing US Strategic Petroleum Reserve releases. #OOTT discussion explores whether it's due to weaker demand, expiring contracts, or operational limits affecting market balance. Read →
Recent video and podcast calls from respected oil and commodity analysts
Kpler: Gulf states may pay Iran Hormuz tolls
Gulf producers may be paying Iran 10 to 20% tolls for safe Hormuz passage. Watch/Listen →
Bloomberg panel: Oil spike worst for markets
Bloomberg The Opening Trade (Oct 8, 2026) · Wed, Oct 8
An oil spike would be just the worst for the global stock rally. Watch/Listen →
Bloomberg: Rising oil cools Wall Street rally
Bloomberg Open Interest (Oct 7, 2026) · Tue, Oct 7
Rising oil and rates cool Wall Street’s record rally. Watch/Listen →
McGlone: High-price cure vs central banks
Most central banks hiked rates in 3Q on the back of the global energy crisis. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
Hormuz traffic returns to normal by December 31
18%
-2pp w/w
US-Iran ceasefire holds through October 31
77%
+17pp w/w
Source: Polymarket
Red Sea / Bab el-Mandeb
Houthi threat to Red Sea shipping; a closure reroutes tankers and LNG around the Cape. Polymarket odds, last 7 days.
Bab el-Mandeb effectively closed by December 31
15%
-2pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed hikes 25 bps at the October meeting
15%
-9pp w/w
US recession by end of 2026
6%
-3pp w/w
Source: Polymarket
Hurricane Season 2026
US Gulf Coast hurricane landfall risk for upstream NG + oil supply. Polymarket odds, last 7 days.
Any Cat 4+ hurricane US landfall before 2027
16%
+11pp w/w
Source: Polymarket
Russia / Ukraine Energy
A ceasefire would shift Russian crude and product flows and European gas pricing. Polymarket odds, last 7 days.
Russia-Ukraine ceasefire agreement by December 31
14%
-1pp w/w
Source: Polymarket
Was this forwarded to you? Subscribe free →
Hedge smarter, not harder.
This newsletter is brought to you by BoxWood · The AI-powered programmatic hedge booking system for commodity producers, consumers, refiners, hedge funds, and trading houses. See a live demo →
Morgan Downey's Commodity News is published by Wooden Table Press LLC. Informational only, not financial or legal advice. Do your own research. No representation is made as to accuracy or completeness.
Unsubscribe · View in browser · Subscribe
Unsubscribe · View in browser · Subscribe