The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Street views · Archive
Friday, October 16, 2026
▶ The 2-minute market brief · video · 1.25x
Listen · the 2‑minute market briefToday's markets in two minutes. Tap to play
Prefer audio only? Listen here.
Markets at a glance
Charts: grey is the prior session, color is today.
Macro
|
S&P 500 Fut
7,806
+0.2%
+15 |
Dollar Index
101.69
-0.4%
-0.36 |
EUR/USD
1.1256
+0.3%
+0.0035 |
US 10Y Yield
5.089
-10 bp
|
Last price as of Fri, Oct 16, 5:35 AM ET · 1-day change vs prior settle. Continuous front-month futures; the dollar index, EUR/USD and the 10-year yield are cash. Click price for news. Dots under the energy tiles: the shape of the curve, cash to 1st to 2nd month, cash from Prism; under Dutch TTF, the first three contracts.
Today's sponsor slot is open. Ask us about it →
Downey's Take
Brent $105.17, down $0.75 (-0.7%) and WTI Crude $97.04, down $0.93 (-0.9%). IEA announced a small diesel stock release ahead of US midterms that is sort of immaterial and had been priced in months ago anyhow.
US potentially lifting sanctions on some shadow fleet oil tankers.
These shadow tankers were previously used for Russian, Iranian or Venezuelan oil, so they could now potentially carry non-sanctioned crude and refined products to cut record freight rates ($30+/bbl Mid East to Asia) and increase Persian Gulf supply.
Of the 160 OFAC-sanctioned supertanker VLCCs (22% of the fleet, nearly a third over 20 years old), estimates are that only 24 could rejoin mainstream trade after age and ownership filters.
100 commercial ships (many tankers) have been attacked near Hormuz since Feb 28.
Coffee up $13.6 (+4.6%) on tighter near-term supplies from Colombia's 15% production drop and El Niño weather risks for Brazil's next crop.
Sugar down $0.42 (-2.0%) on profit-taking after recent highs and new-season crushing hedging in the Northern Hemisphere.
Nickel down $264 (-1.7%) on ample global supply and persistent surplus outlook.
Platinum up $27 (+1.7%) on oversold rebound after Fed rate-hike expectations priced in.
Dutch TTF European nat gas up $1.35 (+1.6%) on reduced LNG flows from the Middle East amid Strait of Hormuz disruptions and low storage levels.
Kicker: Rabobank recommends long European natural gas TTF futures on LNG supply risks from the Middle East and Europe's growing reliance ahead of Russian gas phase-out (Rabobank, Oct 14).
US potentially lifting sanctions on some shadow fleet oil tankers.
These shadow tankers were previously used for Russian, Iranian or Venezuelan oil, so they could now potentially carry non-sanctioned crude and refined products to cut record freight rates ($30+/bbl Mid East to Asia) and increase Persian Gulf supply.
Of the 160 OFAC-sanctioned supertanker VLCCs (22% of the fleet, nearly a third over 20 years old), estimates are that only 24 could rejoin mainstream trade after age and ownership filters.
100 commercial ships (many tankers) have been attacked near Hormuz since Feb 28.
Coffee up $13.6 (+4.6%) on tighter near-term supplies from Colombia's 15% production drop and El Niño weather risks for Brazil's next crop.
Sugar down $0.42 (-2.0%) on profit-taking after recent highs and new-season crushing hedging in the Northern Hemisphere.
Nickel down $264 (-1.7%) on ample global supply and persistent surplus outlook.
Platinum up $27 (+1.7%) on oversold rebound after Fed rate-hike expectations priced in.
Dutch TTF European nat gas up $1.35 (+1.6%) on reduced LNG flows from the Middle East amid Strait of Hormuz disruptions and low storage levels.
Kicker: Rabobank recommends long European natural gas TTF futures on LNG supply risks from the Middle East and Europe's growing reliance ahead of Russian gas phase-out (Rabobank, Oct 14).
Drivers and the Kicker trade idea are sourced from third-party news and bank or desk commentary. Informational only, not trade advice.
The marquee commodity stories of the day
Metals rebound after US inflation shock selloff
Bloomberg News · Bloomberg · Thu, Oct 15, 2026
Copper, aluminum and zinc rebounded in London after a sharp selloff triggered by stronger-than-expected US inflation data and fears of more aggressive Fed tightening. Risk appetite returned to Asia on Friday, with copper snapping a three-day decline. Read →
Oil set for second weekly gain amid Mideast risks
Bloomberg · Thu, Oct 15, 2026
Oil was set for a second weekly advance as mounting Middle East supply risks outweighed a fresh release of emergency reserves. Brent dipped toward $105 a barrel while WTI was near $97, with uncertainty growing over Persian Gulf flows. Read →
IEA accelerates diesel stock release of 20M barrels
Reuters · Thu, Oct 15, 2026
The IEA agreed to accelerate release of remaining volumes from a March pledge, including over 20 million barrels of diesel as soon as possible. Members have released about 330 million barrels so far from the original pledge exceeding 400 million. Read →
US gas futures mixed after below-estimate storage build
Anthony Harrup · Wall Street Journal · Thu, Oct 15, 2026
US natural gas inventories rose by a below-average 67 Bcf last week, narrower than the five-year average build of 90 Bcf and the 75 Bcf estimate. The storage surplus over the five-year average narrowed to 45 Bcf from 68 Bcf. Read →
Oil settles mixed amid Hormuz shipping risks
Farhan Rafid and Anthony Harrup · Wall Street Journal · Thu, Oct 15, 2026
Oil futures settled mixed Thursday with Brent slipping 0.1% to $105.92 a barrel while WTI rose 2.8% to $96.50. Traders weighed a weaker global demand outlook and recovering Middle East supplies against persistent Hormuz shipping risks. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 3US Natural Gas 3Wet Gas, NGLs/LPGs & Petchems 4Global Nat Gas & LNG 4Power 2Coal 1Agriculture 3Fertilizers 3Base Metals 4Iron Ore & Steel 1Precious Metals 2Rare Earths & Critical Minerals 3Shipping & Freight 3Environment 3Real-World Assets & On-Chain Commodities 3Corporate & Deals 3Regulation & Government 1Social buzz 5Watch & Listen 1Prediction Markets
Markets News
Oil
What's moving · WTI jumps 3% on 8.6M barrel US crude stock draw while Brent slips on shadow fleet sanction easing talk.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude | 97.04 | -0.9% -0.93 |
+66.2% | +65.8% | +15.8% |
| Brent | 105.17 | -0.7% -0.75 |
+68.5% | +67.3% | +21.6% |
| RBOB Gasoline | 3.132 | -1.5% -0.048 |
+78.5% | +65.7% | +22.5% |
| Heating Oil | 4.781 | -1.3% -0.065 |
+117% | +111% | +80.5% |
| NY RBOB Crk $/bbl |
34.50 | -3.1% -1.09 |
+126% +19.22 |
+65.2% +13.62 |
+46.2% +10.91 |
| NY HO Crk $/bbl |
103.75 | -1.7% -1.79 |
+204% +69.63 |
+184% +67.16 |
+279% +76.37 |
| NY 321 Crack $/bbl |
57.59 | -2.3% -1.33 |
+167% +36.02 |
+121% +31.47 |
+132% +32.73 |
IEA to release remaining 100M barrels including 20M diesel soon.
Bloomberg · Thu, Oct 15, 2026
IEA members agreed to complete the release of about 100 million barrels still outstanding from the March pledge, including over 20 million barrels of diesel as soon as possible. Members have already released 330 million of the original 400 million barrels. The move aims to boost supply and cool high fuel prices amid ongoing disruptions. Read →
WTI gains 3% after EIA reports 8.6M barrel crude inventory drop.
Maria Eugenia Garcia · DTN · Thu, Oct 15, 2026
EIA data showed US commercial crude stocks fell 8.6 million barrels to 415.6 million in the week to Oct 9, the steepest drop since February and far larger than the expected 288,000-barrel draw. Production fell 300,000 bpd partly due to Hurricane Isaias shut-ins. WTI settled at $97.97, up 3.03%. Read →
Oil edges lower Friday on shadow fleet and IEA release news.
Reuters · Fri, Oct 16, 2026
Brent fell 41 cents to $105.51 and WTI dropped 54 cents in early trade. Markets weighed the IEA's accelerated release of remaining emergency stocks against persistent Middle East risks. The Trump administration is considering easing some shadow fleet sanctions to lower freight rates. Read →
US Natural Gas
What's moving · EIA's 67 Bcf storage build undershoots estimates, lifting November gas futures 2% to $3.26/MMBtu.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub | 3.189 | -1.5% -0.047 |
-13.5% | +6.0% | -36.1% |
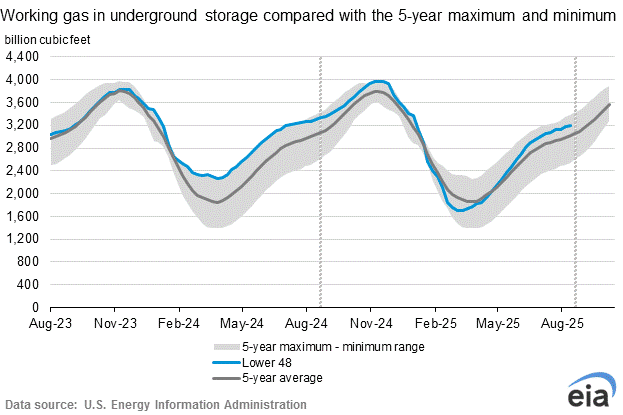
EIA gas storage · week ending Fri, Oct 9
A 67 Bcf injection took working gas to 3,567 Bcf, 45 Bcf (1%) above the five-year average and 143 Bcf below a year ago. That is 7 Bcf below the +74 Bcf consensus, bullish for price.
Working gas 3,567 Bcf +67 Bcf w/w | Year ago 3,710 Bcf | 5-yr avg 3,522 Bcf |
Consensus +74 Bcf this week | Year-ago chg +81 Bcf | 5-yr avg chg +89 Bcf |
Source: EIA Weekly Natural Gas Storage Report · Full EIA report →
Futures climb 2% on smaller storage build and lower output
Reuters via Business Recorder · Fri, Oct 16, 2026
November futures rose 6.4 cents to $3.262/MMBtu after the EIA's 67 Bcf build missed forecasts. Lower 48 output fell to 110.7 bcfd in October from record highs due to Gulf shut-ins from Hurricane Isaias and multiple pipeline force majeures. Demand forecasts rose for next week while LNG feedgas slipped to 17.6 bcfd. Read →
TCO force majeure cuts 1.9 Bcf/d Appalachian capacity
Kevin Dobbs · Natural Gas Intelligence · Thu, Oct 15, 2026
Columbia Gas Transmission declared a new force majeure on its MXP Line effective Oct. 15 evening, eliminating 1.9 Bcf/d of firm service from Appalachian receipts due to a leak in West Virginia. The outage compounds an existing Braxton constraint and contributed to a 1,853 MMcf/d drop in Northeast dry gas production. It supports prices by limiting future storage builds. Read →
Bullish storage print and TCO outage lift November futures
Andrew Baker · Natural Gas Intelligence · Thu, Oct 15, 2026
A below-consensus 67 Bcf EIA storage injection and the major TCO Appalachian pipeline outage drove modest gains in November futures. Robust LNG feedgas demand and production declines from recent hurricanes and force majeures added support. Mild weather forecasts through late October limited broader upside. Read →
Your ad here
One sponsor per issue, and nobody else
This is where a sponsor's block sits: room to actually say what you do, to the people who read this letter every morning.
Email us for target audience and the rates →
Wet Gas, NGLs/LPGs & Petchems
What's moving · Gulf Coast propane stocks draw 1.9 MMbbl as exports rebound and heating demand builds, lifting Mont Belvieu propane to 102.5¢/gal.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.300 | +0.6% +0.002 |
+26.5% | +12.5% | -31.7% |
| Propane C3 $/gal |
1.025 | -0.1% -0.001 |
+66.1% | +59.6% | -30.6% |
| N-Butane NC4 $/gal |
1.683 | +0.1% +0.002 |
+126% | +106% | +3.0% |
| Isobutane IC4 $/gal |
1.861 | -0.9% -0.017 |
+139% | +118% | +13.7% |
| Pentane C5 $/gal |
2.174 | +0.0% +0.000 |
+85.5% | +78.5% | +12.9% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 9 | +1 | +10 | +2 | -2 |
| C3 Frac Sprd ¢/gal | 73 | unch | +45 | +37 | -29 |
| C2 vs NWE Naph $/mt | -670 | +3 | -366 | -363 | -249 |
| C3 vs NWE Naph $/mt | -368 | +1 | -203 | -189 | -377 |
| C5 as % WTI | 94 | +1 | +10 | +7 | -2 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
EIA propane stocks · week ending Fri, Oct 9
A 1.5 mb draw took US propane stocks to 106.4 mb, 13.6 mb (15%) above the five-year average and 4.0 mb above a year ago. Exports ran 1,992 kb/d (-472 kb/d w/w) against production of 2,898 kb/d.
US stocks 106.4 mb -1.5 mb w/w | Year ago 102.4 mb | 5-yr avg 92.8 mb |
Gulf Coast 66.7 mb PADD 3 | Midwest 25.7 mb PADD 2 | Exports 1,992 kb/d -472 kb/d w/w |
Source: EIA Weekly Petroleum Status Report · Full EIA report →
US propane stocks draw 1.5 MMbbl on Gulf Coast pullback
Christine Groenewold · RBN Energy · Thu, Oct 15, 2026
EIA data for the week ended Oct 9 showed total US propane/propylene stocks fell 1.5 MMbbl to 106.4 MMbbl, with the entire draw from PADD 3 (Gulf Coast) at 1.9 MMbbl. Midwest stocks slipped below the five-year average. The draw exceeded expectations and supports tighter near-term balances ahead of winter heating demand. Read →
US propane exports reach record on Europe and Asia demand
World Ports Organization · Fri, Oct 16, 2026
US propane, ethane and butane exports held at 3.2 MMb/d in September with Asia taking the largest share. Europe imports of US propane rose sharply month-on-month. FOB Gulf Coast premiums to Mont Belvieu prices more than doubled to 10.8 ¢/gal, while VLGC rates on Houston-Japan strengthened. Read →
Targa set to overtake Enterprise as top Mont Belvieu fractionator
East Daley · Wed, Oct 14, 2026
Targa’s 150 Mb/d Train 12 due online in 1Q27 will make it Mont Belvieu’s largest fractionator, ending Enterprise’s six-and-a-half-year lead. Rising ethane export demand is tightening fractionation capacity and driving the expansions. Read →
Enterprise ATEX ethane pipeline faces recontracting risk
East Daley · Wed, Oct 14, 2026
Enterprise’s ATEX ethane pipeline from Appalachia faces recontracting risk on 95 Mb/d of capacity in 2028 as tariffs exceed current Mont Belvieu ethane values near 30 ¢/gal. Strong utilization continues but legacy contracts create commercial pressure. Read →
Global Nat Gas & LNG
What's moving · TTF slips 1% to €85.45/MWh as mild weather and storage injections ease immediate pressure amid persistent low EU stocks at 74%.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
87.78 | +1.6% +1.35 |
+207% | +172% | -7.9% |
| Dutch TTF $/MMBtu |
28.96 | +1.6% +0.44 |
+207% | +172% | -7.9% |
| JKM $/MMBtu |
29.34 | – | +175% | +137% | -23.2% |
EU gas storage · gas day Wed, Oct 14
EU gas storage is 74.1% full, 838 TWh in store, 14.8 points below the five-year average for this date and 8.9 points below a year ago. Germany, the bloc's largest store, is 60.2%.
EU full 74.1% +0.08 pts d/d | Year ago 83.0% | 5-yr avg 88.9% same date |
Germany 60.2% |
Source: GIE AGSI+ · Full AGSI+ data →
ING flags Persian Gulf LNG down 80% YoY, low EU storage at <75%.
Warren Patterson · FXStreet / ING · Thu, Oct 15, 2026
ING notes European TTF prices hit highest since Dec 2022 on Persian Gulf LNG flows 80% below year-ago levels. EU storage sits just under 75% full, well below the five-year average of 89%, prompting Germany to direct SEFE to buy and store an extra 8 TWh by mid-Dec. Analysts expect Asia-Europe spot cargo competition to keep prices supported through winter, with TTF now forecast to average €73/MWh. Read →
TTF hits €87.43/MWh intraday on weak Qatari LNG, low storage.
energynews.pro · Wed, Oct 14, 2026
Dutch TTF touched €87.43/MWh intraday, its highest since Dec 2022, driven by weak Qatari LNG deliveries and EU storage below seasonal averages. Qatari Sept exports reached only 1.6 Mt versus pre-war norms, with Oct shipments on track for just 0.6 Mt per Kpler data. EU storage stood at 833.43 TWh as of Oct 12, with Germany at 60% full. Read →
Europe Q3 LNG imports fall 13% YoY to 21.52 Mt.
Business News Report · Fri, Oct 16, 2026
European LNG imports declined 13% year-on-year in Q3 2026 to 21.52 million tonnes. Spain, Germany, Poland and Belgium saw sharp drops while storage stood at 73% as of early Oct, prompting a lowered November target from 90% to 80%. Flows remain tied to price differentials between basins. Read →
JKM holds at $29.78/MMBtu, +$1.34 premium over TTF.
LNGPriceIndex.com · Thu, Oct 16, 2026
Asia’s JKM benchmark sits at $29.78/MMBtu, flat on the day but maintaining a $1.34/MMBtu premium to European TTF at $28.44/MMBtu. Non-Middle East physical premiums remain elevated amid tight charter markets. Key drivers include seasonal demand, exporter availability and the Europe-Asia arbitrage window. Read →
Power
What's moving · FERC orders PJM, MISO, SPP, CAISO and others to justify or reform large-load tariffs within 60 days amid data-center demand surge.
FERC orders six US grid operators to justify or reform large-load tariffs in 60
Federal Energy Regulatory Commission · Thu, Oct 15, 2026
FERC issued show-cause orders under Section 206 to PJM, MISO, SPP, CAISO, ISO-NE and NYISO directing each to justify current tariffs for data centers and other large loads or file reforms addressing interconnection, cost allocation, co-location and generation adequacy. The orders build on prior actions including PJM co-location rules and SPP's High Impact Large Load processes. This targets speed-to-power for AI and manufacturing while protecting ratepayers as large-load interconnection queues grow rapidly. Read →
Nord Pool day-ahead prices 16 Oct: all 15 zones hourly
progrunners.com · Fri, Oct 16, 2026
Nord Pool's single European day-ahead auction for Oct 16 produced wide spreads, with SE1 at 15.9 EUR/MWh daily average and DK1 at 209.6 EUR/MWh; other zones included SE3 at 76 EUR/MWh and FI at 17 EUR/MWh. Prices reflect the SDAC auction results published via ENTSO-E Transparency Platform. No negative prices reported in the Nordic/Baltic zones for the day. Read →
Coal
What's moving · Asian thermal coal prices hit two-year highs on winter stockpiling amid China/Indonesia supply curbs and high gas prices.
Indonesia policy uncertainty delays 2027 coal contracts with protective clauses
Pritish Raj · S&P Global · Thu, Oct 15
Indonesian miners and Asian buyers are delaying 2027 term supply deals due to uncertainty over RKAB production quotas, DMO obligations, and the new DSI export oversight body effective January 2027. Miners are adding protective clauses tying commitments to approved quotas. Expected 2026 output is 720 to 730 million tonnes versus 790 million in 2025, tightening seaborne availability and supporting prices like Platts FOB Kalimantan 4,200 kcal at $78.55/t on Oct 14. Read →
Agriculture
What's moving · US harvest acceleration and Chinese soybean purchases drive mixed grain futures amid ample supply.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn | 478 | -0.1% -0 |
+8.5% | +13.1% | -10.3% |
| Wheat | 665 | -0.8% -6 |
+31.1% | +31.9% | -9.7% |
| Soybeans | 1,261 | -0.2% -2 |
+22.3% | +23.7% | +3.2% |
| Sugar | 20.71 | -2.0% -0.42 |
+38.0% | +33.6% | +7.0% |
| Coffee | 308.4 | +4.6% +13.6 |
-11.6% | -22.4% | +53.0% |
| Cocoa | 5,802 | -0.5% -29 |
-4.3% | -1.6% | +122% |
| Cotton | 80.56 | +0.6% +0.50 |
+24.7% | +24.6% | -25.1% |
Soy futures fall on US harvest surge despite China buys
Reuters · Thu, Oct 15, 2026
Chicago Board of Trade soybean futures dropped 0.4% to $12.71 to 3/4 per bushel on Thursday as dry Midwest weather sped up harvesting, with 46% of the US soybean crop now in the bin, above analyst expectations. Losses were capped by Chinese government buyers booking 8 to 10 cargoes of US soybeans for December and later shipment, confirmed by a 470,000 metric ton private export sale to China. Active harvest supplies and a one-year low expected September crush weighed on prices. Read →
Grains ease Friday but post weekly gains on short covering
MillingandMillers.com · Fri, Oct 16, 2026
Chicago wheat fell 0.4% to $5.72 to 1/2, corn slipped 0.1% to $4.10 to 1/4 and soybeans dropped 0.2% to $10.21 to 1/2 on Friday as funds turned net sellers after a two-week rally from near four-year lows. All three posted weekly gains of 4.2%, 2.2% and 2.1% respectively on speculator short covering, a weaker dollar and poor European wheat crops. Traders await next week's USDA September crop estimates amid expectations of large US corn and soy harvests. Read →
China flash sales support soybeans; Brazil output rises
ADM Investor Services · Thu, Oct 15, 2026
USDA confirmed flash sales of 330,000 metric tons of soybeans to China and 283,500 metric tons to unknown buyers for 2026 to 27 delivery. November soybeans hit a seven-week low despite the purchases as harvest pressure mounted. Conab raised its 2026/27 Brazil corn production forecast to 148 million metric tons and soybean output to 181.6 million metric tons, above prior USDA projections. Read →
Fertilizers
What's moving · Hormuz sulfur squeeze and China phosphate export collapse tighten phosphates while India urea tender prices drop sharply.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Urea, China (ZCE) CNY/t |
1,676 | +1.1% +18 |
-4.2% | +4.5% | -45.5% |
| Urea, Egypt FOB $/t |
502.50 | +0.0% +0.00 |
-12.6% | +15.3% | -37.8% |
| Urea, Brazil CFR $/t |
478.00 | +0.4% +2.00 |
+17.3% | +12.7% | -38.7% |
| Urea, US Gulf FOB $/st |
437.00 | +0.5% +2.00 |
+13.0% | +15.2% | -38.3% |
| DAP, NOLA FOB $/st |
802.50 | +0.0% +0.00 |
+28.4% | +4.6% | +17.1% |
The 5Y column starts from the October 2021 peak, when the European gas crisis shut ammonia plants and China halted urea exports. Daily settles; these contracts barely trade, so flat days are common.
Hormuz disruption and Canada risks squeeze NPK supplies
Agro News Today / Michigan Ag Today · Thu, Oct 15, 2026
StoneX's Josh Linville said Strait of Hormuz disruption threatens urea, ammonia, phosphate and sulfur supplies from Iran, Qatar and Saudi Arabia, with half the world's tradable sulfur passing through the strait. US potash imports rely 90% on Canada amid USMCA uncertainty. High sulfur prices force US and other phosphate production cuts even as demand weakens. Read →
China phosphate exports near zero on sulfur squeeze
Fertilizer Daily / UkrAgroConsult · Fri, Oct 16, 2026
China halted nearly all phosphate fertilizer exports in 2026 after shipping 5.3 million tonnes in 2025, as tight sulfur supplies and Beijing policy prioritize domestic use while restricting sulfuric acid exports. Argus sees only a partial rebound to about 2 million tonnes in 2027. The move adds pressure on import-dependent markets already facing elevated sulfur and ammonia costs. Read →
UAN32 leads US retail fertilizer prices higher
Russ Quinn · DTN Progressive Farmer · Wed, Oct 14, 2026
Average US retail urea reached $672/ton in early October, up $14 from a month earlier and 12% above year-ago levels. UAN32 rose 6% month-over-month to $485/ton while all eight major nutrients exceeded year-ago prices, led by anhydrous ammonia up 20%. Potash crossed back above $500/ton for the first time since August 2024. Read →
Base Metals
What's moving · US inflation data beat expectations, lifting rate-hike odds and dollar to push LME copper down 0.88% overnight to $14,309/mt.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
14,611 | +1.1% +157 |
+17.7% | +34.4% | +40.1% |
| Copper SHFE $/mt |
14,487 | -0.2% -29 |
+14.1% | +35.6% | +51.8% |
| Aluminium SHFE $/mt |
3,069 | +0.4% +13 |
+3.1% | +17.5% | -2.3% |
| Zinc SHFE $/mt |
3,365 | -0.7% -23 |
+12.0% | +22.3% | +7.3% |
| Nickel SHFE $/mt |
15,265 | -1.7% -264 |
-9.9% | +0.7% | -22.3% |
| Lead SHFE $/mt |
2,143 | -0.3% -7 |
-2.7% | +1.4% | +7.4% |
| Tin SHFE $/mt |
49,949 | +1.0% +505 |
+18.9% | +41.2% | +30.4% |
Hotter US PPI and retail sales push LME, SHFE copper lower.
Shanghai Metals Market (SMM) · Fri, Oct 16, 8:58 AM ET
US September PPI rose 6.3% YoY and retail sales 0.8% MoM, both above forecasts, lifting Fed rate-hike bets. LME copper fell 0.88% to $14,309/mt with increased short positions; SHFE copper dropped 0.71%. Easing Escondida strike risk added selling pressure on the metal. Read →
LME base metals drop as dollar retreats from highs.
Shanghai Metals Market (SMM) · Fri, Oct 16, 8:31 AM ET
LME copper fell 1.25%, zinc 1.21% and nickel 1.68% overnight while aluminum held flat. SHFE nickel dropped 1.67% and zinc 0.8%; tin rose 1.22%. Dollar index eased 0.55% from its 18-month high after stronger US data. Read →
LME copper edges up Friday but eyes weekly loss.
Business Recorder / Reuters · Fri, Oct 16, 11:45 AM ET
Three-month LME copper rose 0.3% to $14,383.50/mt early Friday but remains down about 1% for the week. SHFE copper slipped 0.1%. Analysts cite AI-stock selloff spillover and persistent inflation concerns weighing on the complex. Read →
Copper hits 10-day low on profit-taking and macro data.
Staff Writer · MINING.COM · Thu, Oct 15, 9:12 AM ET
LME copper fell toward a 10-day low after Escondida union deal removed strike risk and hotter US CPI revived rate-hike odds. COMEX copper dropped 1.2%; analysts noted double pressure from easing supply worries and macro tightening expectations. Read →
Iron Ore & Steel
What's moving · Iron ore futures rebound from two-year low on dip buying as steel mill profitability edges up to 8%.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
89.0 | +0.2% +0.2 |
-11.6% | -8.9% | -13.4% |
| Rebar SHFE $/mt |
410 | +0.5% +2 |
+4.1% | +7.0% | -48.2% |
| HRC SHFE $/mt |
426 | +0.3% +1 |
+3.3% | +4.7% | -46.7% |
Iron ore rebounds from two-year low on dip buying
Reuters · Fri, Oct 16, 2026
Iron ore futures on Dalian rose 0.22% to 673.5 yuan/t and SGX November contract gained 0.56% to $90.35/t after hitting lows Thursday. The rebound followed Mysteel data showing 8% of Chinese steelmakers profitable on Oct 15 versus 6.9% prior week, slowing hot metal output declines and signaling restocking needs. Port inventories continued building, capping gains. Read →
Precious Metals
What's moving · Hot September PPI at 6.3% annual lifts inflation-hedge bids, sending gold up 1.5% to $4,148/oz as yields and dollar ease.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold | 4,207 | +0.9% +37 |
-3.1% | -0.1% | +138% |
| Silver | 58.05 | +1.6% +0.89 |
-17.2% | +16.4% | +150% |
| Platinum | 1,649 | +1.7% +27 |
-19.0% | +2.9% | +59.1% |
| Palladium | 1,134 | +0.4% +5 |
-30.4% | -24.4% | -43.8% |
Gold futures rise 1.5% to $4,147.70 as yields and dollar fall.
Anthony Harrup · Wall Street Journal · Thu, Oct 15, 2026
Comex front-month gold gained $62.90 or 1.54% to settle at $4,147.70 after snapping a three-session losing streak. A drop in U.S. Treasury yields and a weaker dollar outweighed the impact of hotter-than-expected inflation data. Central bank buying continues to cushion downside risks despite the recent volatility. Read →
Hot PPI spurs inflation-hedge buying; gold and silver rebound.
USAGOLD · Thu, Oct 15, 2026
September PPI jumped 1.3% month-over-month, the largest gain in over four years, lifting the annual rate to 6.3%. Gold spot advanced to $4,175.90 (+1.24%) and silver to $57.55 (+1.99%) in early U.S. trade as softer yields and dollar supported the rebound. The data reinforced precious metals’ role as an inflation hedge ahead of further Fed signals. Read →
Rare Earths & Critical Minerals
What's moving · US firms scout Malaysia rare earth projects as China export controls near Nov 10 deadline.
US firms explore Malaysia rare earth projects to cut China reliance
Bloomberg · Wed, Oct 14, 2026
More than a dozen unnamed US companies are exploring mining projects and processing investments in Malaysia with local partners. The US Embassy in Kuala Lumpur confirmed the activity as Washington diversifies critical mineral supplies away from China. This accelerates friend-shoring in the permanent-magnet supply chain ahead of the November 10 suspension expiry on China's expanded export controls. Read →
Europe antimony market stabilizes amid weak demand
Sebastian Evelyn · Fastmarkets · Thu, Oct 15, 2026
Fastmarkets assessed European antimony metal at $18,300 to 19,000 per tonne on October 14, unchanged since early September. Weak downstream demand and ample warehouse stocks have created a stalemate with limited liquidity. China's 2024 export controls and July 2026 additions to its list continue to shape two-tier pricing, though recent measures targeted specific firms rather than blanket metal bans. Read →
Lindian nears December monazite concentrate output in Malawi
PR Newswire / company announcement · Thu, Oct 15, 2026
Lindian reported ore stockpiles at 149,000 tonnes, up 19% from September, with 33kV power line commissioned and transformers on site. Separation circuits are 80 to 90% complete and operator training has begun. First monazite concentrate production remains targeted for December 2026, adding non-Chinese supply of neodymium-praseodymium and other rare earths. Read →
Shipping & Freight
What's moving · Baltic Dry Index slumps 4.6% to 2,545, its lowest since June 30, on Capesize weakness.
| Route | $/day | Wk | 1Y | $/t | $/bbl |
|---|---|---|---|---|---|
| VLCC TD3C MEG to China |
$1.48M | +15.8% | +2395% | $245.3 | $33.47 |
| Suezmax TD20 WAF to UKC |
$590k | +37.5% | +1204% | $161.5 | $22.03 |
| Aframax TD25 USG to UKC |
$325k | +35.3% | +739% | $181.5 | $24.76 |
| LR2 TC1 MEG to Japan |
$282k | +0.1% | +1167% | $185.1 | $24.85 |
| LR1 TC5 MEG to Japan |
$206k | -1.2% | +1208% | $194.8 | $21.89 |
| MR TC18 USG to Brazil |
$45k | -31.9% | +47.9% | $70.2 | $8.26 |
| MR TC7 Singapore to Aus |
$76k | -13.6% | +267% | $103.6 | $13.91 |
Report of Oct 8, 2026. Weekly round-voyage TCE and freight cost per tonne and per barrel; TD routes carry crude, TC routes refined products. 1Y is the $/day change; Prism's history starts in October 2023, so there is no 5Y. Source: Prism, from the E.A. Gibson tanker report.
Baltic Dry Index hits lowest since June 30 on Capesize slump
Anushree Mukherjee · Reuters via Baird Maritime · Thu, Oct 15, 6:02 PM ET
The Baltic Exchange dry bulk index fell 122 points or 4.57% to 2,545 on Thursday, marking its ninth straight decline and lowest level since June 30. The Capesize index plunged 308 points or 8.48% to 3,322, its lowest since early April, with average daily earnings dropping $2,792 to $26,625; Panamax also fell while supramax edged up. Iron ore prices slipped for a third session to multi-year lows amid weak Chinese demand. Read →
VLCC rates climb to record levels on key routes
Cyprus Shipping News · Thu, Oct 15, 2026
Baltic VLCC assessments rose sharply this week with TD3C Middle East Gulf-China reaching WS1,318.75 for a round-trip TCE of $1.41 million per day. Atlantic routes also strengthened, including West Africa-China at WS750.63 ($763k/day TCE) and US Gulf-China surging to a $637k/day TCE. Suezmax and Aframax segments posted broad gains across West Africa, Black Sea, North Sea and Mediterranean routes. Read →
Suez Canal container transits exceed 50% of pre-crisis levels
Maritime News · Thu, Oct 15, 2026
Weekly container-ship capacity through the Suez Canal averaged 753,000 TEU in the first two weeks of October, exceeding 50% of the 1.457 million TEU pre-disruption level for the first time. Large containership activity strengthened October 12 to 14 with CMA CGM Pantheon making its maiden transit; Suez Canal Authority data showed 166 medium and ultra-large vessels (over 130,000 net tons) transited July-September for 29 million net tons. Recovery follows multiple carriers restoring Asia-Europe services though volumes remain below 2023 peaks. Read →
Environment
What's moving · EU leaders call for faster MSR reform to curb EUA price volatility amid energy weakness.
EU leaders urge faster MSR reform to curb EUA volatility
Carbon Pulse · Fri, Oct 16, 2026
EU leaders adopted summit conclusions overnight calling for accelerated talks on reforming the Market Stability Reserve (MSR) to reduce excessive carbon price volatility while preserving the ETS role in driving clean energy investment. The move comes as six countries push to delay ETS2 for transport and heating until at least 2030 amid energy crisis talks. Faster MSR reform could stabilize EUA prices and support compliance demand in the EU ETS. Read →
EUAs slip lower as gas, power prices weaken on mild weather
Carbon Pulse · Thu, Oct 15, 2026, 5:10 PM ET
European carbon allowance prices slid lower in lacklustre trading on Thursday amid gloomy industrial production data, weaker gas and power prices, and forecasts for continued mild weather. The decline erases some recent gains and highlights sensitivity to near-term energy fundamentals. Mild weather reduces heating demand and power-sector EUA buying pressure. Read →
California issues 1.3M compliance offsets mostly to mine methane capture
Carbon Pulse · Wed, Oct 15, 2026
California issued roughly 1.3 million compliance-grade offsets in its second-largest bimonthly round year-to-date, mostly to mine methane capture projects, per state data published Wednesday. The supply addition supports compliance entities in the California-Québec market. Offsets help meet obligations and can ease pressure on CCA allowance demand. Read →
Real-World Assets & On-Chain Commodities
What's moving · Hyperliquid adds crude oil perpetual futures amid $9B RWA perp open interest surge.
Hyperliquid adds Nvidia and crude oil perpetual futures.
Benzinga via KuCoin · Thu, Oct 15, 2026
Hyperliquid launched perpetual futures on Nvidia and crude oil via protocol update. Deployers stake 500,000 HYPE tokens for Dutch-auction listings. CEO Jeff Yan framed the move as advancing 24/7 on-chain trading toward housing all finance. Read →
Ripple Prime launches RWA perpetual swaps on Hyperliquid.
Yogita Khatri · The Block · Thu, Oct 15, 2026
Ripple Prime rolled out institutional RWA perpetual swaps referencing Trade.xyz markets on Hyperliquid. The swaps span equities, indices, ETFs, metals, energy and FX with 24/7 trading and RLUSD collateral. Virtu is among early institutional users. Read →
RWA perpetual open interest hits $9 billion across five venues.
Enna Lee · TokenPost · Thu, Oct 15, 2026
RWA perpetual open interest reached roughly $9 billion, or 14% of the $67 billion sample total across five venues. Ripple Prime's Hyperliquid-linked launch added institutional access. The figure reflects rapid growth from near-zero levels a year prior. Read →
Industry News
Corporate & Deals
What's moving · NFG board approves tax-free spin-off of Seneca/IUG Marcellus gas assets into standalone driller, expected H2 2027.
NFG board OKs tax-free spin-off of Seneca Marcellus gas assets
Business Insider / GlobeNewswire · Thu, Oct 15, 2026
National Fuel Gas (NFG) board approved spinning off its Integrated Upstream and Gathering (IUG/Seneca Resources + midstream) Appalachian natural gas business into a standalone public company via tax-free distribution of at least 80.1% of shares to NFG shareholders. IUG will hold 1.2 million net acres, 1.1 Bcf/d net production and 5 Tcf proved reserves; NFG retains up to 19.9% initially. Post-spin, NFG becomes a pure regulated utility with $5 billion rate base serving 1.1 million customers. Separation expected H2 2027; Justin Loweth to lead IUG as CEO. This separates upstream/gathering from regulated assets amid strong Appalachian gas demand from power and data centers. Read →
Alcoa posts Q3 net income $483M on strong cash flow, Alumar restart
Business Wire / Yahoo Finance · Thu, Oct 15, 2026
Alcoa reported Q3 2026 revenue of $3.704 billion, net income attributable to the company of $483 million ($1.81/share) and adjusted net income of $485 million ($1.82/share). Adjusted EBITDA excluding special items was $789 million; cash from operations reached $643 million with free cash flow of $472 million. Aluminum production rose for the sixth straight quarter with year-to-date records at five smelters and one refinery; the Alumar, Brazil smelter restart was completed. South32 shareholders approved the AliGroup acquisition on Oct 15, advancing the deal toward H1 2027 close; company ended quarter with $4.4 billion cash including $2.6 billion financing for the transaction. Read →
Capital Ltd Q3 revenue rises 23% YoY to $115.7M, raises 2026 guidance
Investegate / company announcement · Thu, Oct 15, 2026
Capital Limited reported Q3 2026 group revenue of $115.7 million, up 23.2% year-over-year though down 1.4% sequentially, with nine-month revenue at $334.7 million (+32.2% YoY). Mining revenue jumped 223% YoY to $25.2 million while MSALABS laboratory revenue rose 23.8% YoY to $26.0 million; drilling revenue was broadly flat. The company raised full-year 2026 revenue guidance to $435 to 455 million (from prior $430 to 450 million) to reflect consolidation of the newly acquired Australian underground drilling contractor Metres Down Under (MDU) from Sept 30. MDU is expected to be accretive from day one. Read →
Regulation & Government
What's moving · US weighs easing shadow fleet sanctions and pushes World Bank to fund upstream oil and gas amid diesel crunch.
Bessent urges World Bank to end upstream oil and gas ban
Reuters · Thu, Oct 15, 2026
US Treasury Secretary Scott Bessent called for the World Bank to drop its prohibition on financing upstream oil and gas projects. He also pushed for more support for deep-sea critical minerals mining and reforms to procurement policies. The US is making an initial contribution to a new World Bank nuclear energy trust fund. Read →
What traders and commodity market feeds are talking about
Biggest crude and product draw since April tightens inventories
X / multiple traders · Thu, Oct 15
Rory Johnston and traders highlighted the largest weekly US commercial petroleum draw in months, led by crude, diesel and NGLs. Crude fell below seasonal lows at a time when builds are typical. This signals tighter physical balances heading into winter and supports price strength. Read →
IEA speeds diesel stock release to ease crunch into 2027
X / multiple traders · Thu, Oct 15
Reuters reported the IEA will expedite releases including more than 20M barrels of diesel amid thin inventories from Middle East and Russian refinery outages. Traders note the global diesel crunch could persist into mid-2027. This underscores winter supply risks despite higher crude flows. Read →
Diesel demand jumps 673k b/d while stocks drop 2.5M bbl
X / multiple traders · Thu, Oct 15
Jack Prandelli and energy traders noted implied US oil demand rose nearly 1M b/d week-over-week, led by distillates and propane. Distillate stocks are now 12% below the five-year average. The data points to building winter pressure as overseas buyers compete for tight barrels. Read →
Propane at $1.05/gal up sharply on tight supplies
X / @EnergyInvest0r · Thu, Oct 15
EnergyInvestor highlighted Texas propane prices surging to around $1.05 per gallon, up 23% from September and 68% year-over-year. The move benefits producers like Peyto with strong Q4 output. It reflects broader NGL tightness amid the petroleum stock draw. Read →
Strategic Petroleum Reserve at 283M barrels, down 61% from peak
X / multiple traders · Thu, Oct 15
OilPrice.com and #OOTT traders flagged the US Strategic Petroleum Reserve steady at 283M barrels, the lowest since 1982. The thin cushion comes as Hormuz disruptions continue. Traders see limited emergency buffer if further supply shocks hit. Read →
Recent video and podcast calls from respected oil and commodity analysts
Currie: All oil risks strictly upside; gasoline worsens
Jeff Currie on Bloomberg TV · Thu, Oct 15
All the risks are strictly to the upside. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
Hormuz traffic returns to normal by December 31
12%
-6pp w/w
US-Iran ceasefire holds through October 31
82%
+5pp w/w
Source: Polymarket
Red Sea / Bab el-Mandeb
Houthi threat to Red Sea shipping; a closure reroutes tankers and LNG around the Cape. Polymarket odds, last 7 days.
Bab el-Mandeb effectively closed by December 31
14%
-1pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed hikes 25 bps at the October meeting
14%
-1pp w/w
US recession by end of 2026
7%
+1pp w/w
Source: Polymarket
Hurricane Season 2026
US Gulf Coast hurricane landfall risk for upstream NG + oil supply. Polymarket odds, last 7 days.
Any Cat 4+ hurricane US landfall before 2027
8%
-4pp w/w
Source: Polymarket
Russia / Ukraine Energy
A ceasefire would shift Russian crude and product flows and European gas pricing. Polymarket odds, last 7 days.
Russia-Ukraine ceasefire agreement by December 31
15%
+1pp w/w
Source: Polymarket
Was this forwarded to you? Subscribe free.
The cash price of physical crude oil, all the time.
This newsletter is brought to you by Prism, free real‑time cash prices for physical crude oil around the world, plus refined products, freight, natural gas and power. See today’s prices.
Morgan Downey's Commodity News is published by Wooden Table Press LLC. Informational only, not financial or legal advice. Do your own research. No representation is made as to accuracy or completeness.
Unsubscribe · View in browser · Subscribe
Unsubscribe · View in browser · Subscribe